
Open Banking deposits use a payment provider to connect the casino cashier with a bank account, where the account holder approves the payment.
How Open Banking Connects a Casino Deposit to a Bank Account
An Open Banking deposit links a casino payment to a bank account without treating the casino itself as the bank. The payment begins in the casino’s cashier, but the customer’s bank remains the place where the account holder authenticates and approves the transaction. In practice, a payment provider sits between the two services: it passes the payment request to the bank and returns a response to the casino.
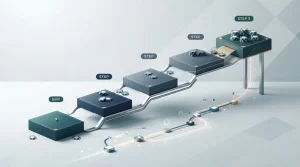
The process is easiest to understand as a hand-off. The casino creates a request for a deposit. A payment service then presents the available bank choices, and the customer selects their bank. The bank’s own authentication process follows, often through its app or online banking. Once the payment has been approved, the bank processes it and the provider sends the outcome back to the casino.
That sequence matters. A deposit is not simply a bank transfer typed out manually, with account details copied into a separate banking screen. Nor does it mean the casino can freely operate the account. The payment depends on a specific approval, made through the bank’s authentication process, for the transaction being presented. The casino sees the payment result and relevant transaction information, not unrestricted control of the account.
I have seen payment screens make this look like one continuous action. Behind the neat button, however, several systems need to agree: the casino’s cashier, the payment provider, the bank’s authentication service and the bank’s payment processing. A decline or interruption at any point can leave the deposit incomplete. That is why a cashier confirmation and a bank-side transaction record are useful ways to understand what happened if a payment appears to stall.
The bank approves; the casino records
The payment provider’s role is to connect the casino’s request with the bank’s approval flow. It may initiate the payment on the customer’s behalf, under the relevant permissions and bank procedures. The bank verifies the customer and asks for approval in its own environment. Once the bank gives a response, the provider passes that status back to the casino, which can then update the account balance.
UK Credit Card Casino Sites: What the Rules Allow
This is the core of Open Banking at an online casino in the UK: a bank-linked route that uses regulated interfaces to request a payment, rather than relying on the casino to hold the customer’s banking credentials. The exact screens and provider names can differ, and a casino may not present the route under the words “Open Banking”. A label such as “pay by bank” may describe a similar bank-connected checkout, but the label alone does not establish how a particular service works.
There is also a distinction between authorising a payment and seeing it reflected in the casino account. The bank may approve the request, while the casino is still waiting for confirmation from the provider. If a page is closed during the hand-off, the payment can be difficult to read from the screen alone. The transaction may be pending, declined or completed; those states are not interchangeable. The cashier’s status and the bank’s record provide separate pieces of the picture.
UK Casino Sites That Accept Jeton: What to Check
Why it can feel immediate
With a conventional bank transfer, a customer may need to leave the casino, enter beneficiary details and arrange the transfer through online banking. An Open Banking payment can bring those steps into a connected checkout and return a status to the casino as part of the same flow. That can reduce manual handling and make a deposit available quickly when the payment is accepted and the casino updates the account.
The speed claim still needs careful wording. A specialist review reports that Open Banking and bank transfers can support instant deposits and fast withdrawals at many sites. That describes a capability, not a promise for every casino, bank, account or transaction. The payment route may be quick while a bank’s response, a provider interruption or the casino’s account update takes longer. The word “instant” describes the intended payment experience; it does not remove the separate steps that have to complete.
While Open Banking can support instant deposits and fast withdrawals, this describes a technical capability rather than a guarantee for every casino, bank, or transaction.
Withdrawals involve a different direction of travel. A casino may use a bank-linked service to send money towards an account, but the payment still has to be initiated and processed through the relevant systems. The fact that a deposit was approved through Open Banking does not, by itself, explain how a particular casino handles a payout. Deposit and withdrawal functions should be understood as distinct parts of the payment arrangement.
A bank-linked route also depends on the bank and account being available in the payment flow. If the selected bank is not shown, authentication fails or approval is declined, the deposit cannot proceed through that route. The cashier may offer another method, but that is a separate choice rather than a continuation of the same Open Banking payment.
From the operational side, the main advantage is a clear chain of events: a casino request, bank authentication, payment approval and a confirmation returning to the casino. The route can remove some manual steps, but it is not magic. Banks still decide whether to authenticate and process a request, providers still relay the result, and casinos still need to record it correctly. That is the mechanism beneath the button.
What “Direct Banking” Means at an Online Casino
“Direct banking” is a payment label, not a precise description of one universal service. At an online casino, it generally points to a route in which a bank account is central to the transaction, rather than a separate prepaid balance or an e-wallet account. Open Banking is one way that bank-linked payments can be arranged, but the terms are not interchangeable: a casino may describe a payment as direct banking without explaining the technical route behind it.
That distinction matters because the wording can make different arrangements sound identical. A bank transfer, a payment initiated through an Open Banking service and a casino cashier option branded as “banking” may all involve a bank account, but they do not necessarily work in the same way. The label alone does not establish which service is being used, how the account is identified, or what information the casino receives. Those details belong to the payment option’s terms and the transaction flow.
I have seen payment names treated as if they were product specifications. They are not. “Direct” describes the impression of a route from a bank account to a merchant; it does not, by itself, confirm that the payment uses Open Banking or that every stage is handled directly by the bank. The useful question is what account is being used and how the casino’s payment route connects that account to the transaction.
Open Banking provides a broader framework for bank-account services. In casino payment language, the term is often used to describe a bank-linked way to make a payment, but the cashier’s label may be more prominent than the underlying arrangement. A casino with Open Banking may present the option under a provider name or a general banking heading. Conversely, seeing the words “bank transfer” does not prove that the payment is an Open Banking payment. The wording needs to be read in context.
There is also a difference between the bank account and the payment route. The account is where the funds are held; the route is the means by which a payment is initiated and recorded. A customer may see a familiar bank name during a transaction, but that fact alone does not explain every party or step involved. It is better to treat the cashier’s description as a starting point, not as a full account of the service.
Using a bank account that does not belong to the account holder can create a mismatch in ownership details and lead to transaction friction.
From an operational perspective, the account details matter because a payment is not just an amount moving between two balances. The casino needs a transaction it can associate with the customer’s account, and basic ownership details can become relevant when that association is unclear. When the account information and the payment route belong to the same customer, there is less scope for avoidable friction caused by mismatched ownership details.
The cleanest arrangement is often a single named account used consistently for both deposits and withdrawals. That is not a promise that every transaction will be accepted without review, nor does it define how a casino handles every case. It is a straightforward way to keep the identity attached to the account and the payment route aligned. Different names or account details can make a transaction harder to reconcile.
“Seamless” is the sort of word that hides this practical point. The underlying expectation is not magic; it is consistency. If a casino’s payment process asks for an account in the customer’s own name, using an unrelated person’s account creates an obvious mismatch. Even where a payment appears to have gone through, that does not make the account relationship irrelevant.
The phrase “Open Banking casino” can therefore refer to a casino that offers a bank-linked payment route, rather than to a separate type of casino. The casino itself is not transformed by the payment technology. What changes is the way a customer’s bank account is used in connection with a transaction. This keeps the term in proportion: it describes a payment arrangement, not a guarantee about the casino’s broader service or about the outcome of an individual payment.
TRON Casino Comparison for the UK: Licensing
The same care applies to “direct bank payment”. It may be a convenient shorthand in a cashier, but shorthand is not a substitute for the specific terms shown before confirming a transaction. The name of the option, the account selected and the route presented should make sense together. A bank logo or a broad “direct” claim is not enough to establish that the customer is using the same account consistently.
In plain terms, direct banking at an online casino means a bank account is part of the payment route. Open Banking may provide the framework for that route, but the label does not tell the whole story. Account ownership is the practical anchor; consistency is what keeps the arrangement clear.
Instant Deposits, Withdrawals and the Bonus Catch
The appeal of an Open Banking deposit is easy to understand: the payment can move from a bank account to a casino balance without the familiar wait associated with some manual transfers. A specialist casino review describes Open Banking and bank transfers as offering instant deposits and fast withdrawals at many sites. That is a description of what a payment route may support, not a promise that every transaction will arrive immediately.
Why is the word “instant” used?
It typically describes the intended payment experience and the capability of the route to move funds quickly, but it does not remove the separate processing steps that must be completed.
The word “instant” tends to describe one part of the journey. A deposit may appear in the casino account quickly, while a withdrawal still has to pass through the operator’s process before money is sent. Those are separate events, handled at different stages. I have seen the distinction get lost in payment-page language: a quick way to fund an account is presented as if it says something definite about getting funds back. It does not.
The deposit is only the first stage
With a bank-linked payment, the customer authorises a transfer through a connected bank account. If the casino and payment service support the route, the balance may update promptly. That can make an Open Banking casino deposit feel more direct than a transfer entered manually through online banking.
But the casino balance is not the same thing as money received from a withdrawal. A withdrawal request may need internal approval, and first withdrawals can take longer while account verification is completed. A specialist casino review notes both the approval stage and the possibility of extra time for an initial payout. So “instant banking” can be accurate about the deposit and still tell little about the full return journey.
Casinos That Accept Diners Club in the UK
That distinction matters when a site advertises an “instant withdrawal”. The phrase may describe a method that can send an approved payment quickly; it cannot remove the operator’s checks or guarantee that a request is approved at once. The payment route and the casino’s processing are connected, but they are not one clock. Different stages. Different conditions.
The bonus is a separate decision
A payment method does not, by itself, establish eligibility for a welcome offer, no-deposit bonus or free spins. Promotion rules are set separately from the cashier options, and the terms attached to an offer determine whether a particular deposit method qualifies. A bank-linked payment appearing in the deposit menu is not evidence that it counts towards a promotion.
This is where “easy” can become misleading. The deposit may be straightforward, but the bonus may have a method restriction, or may require a qualifying deposit made in a particular way. The same offer can also carry conditions unrelated to payment, so the headline alone cannot settle eligibility. The operational point is simple: the cashier and the promotion terms answer different questions.
Do
- Check promotion rules separately from cashier options
- Review qualifying deposit methods in the terms
Don’t
- Assume payment availability implies bonus eligibility
- Mistake a straightforward deposit for a guaranteed offer
PayPal illustrates the distinction. A specialist casino review describes it as valued for speed and convenience while noting that it may be excluded from bonus eligibility. That is a report about a possible restriction, not a rule for every casino or offer. Payment availability should not be read as an assurance about bonus treatment.
The same care applies to claims about an Open Banking casino with a no-deposit bonus or free spins. Those offers are promotional terms, not a feature built into the banking connection. A payment route can make a deposit possible; it cannot create an offer or override its conditions. Nor does an offer’s presence show that every listed payment option is eligible.
In practical terms, the useful comparison is between the time a deposit takes to appear, the operator’s handling of a withdrawal, and the written eligibility rules for a promotion. Keeping those separate prevents a fast deposit from being mistaken for a fast payout, or a visible bonus from being mistaken for a bonus attached to every payment method. The cashier handles the money in; the terms decide the offer; the withdrawal process determines what happens next.
What “Best” Direct-Banking Sites Need to Get Right
When choosing a casino that accepts direct banking, payout timing is one practical detail to check. The entries below list the stated withdrawal timeframe for each operator.
1. Zombillion
Payout speed: 1-3 business days
Zombillion lists a payout speed of 1–3 business days.
2. SlotoSport
Payout speed: 1-3 business days
SlotoSport lists a payout speed of 1–3 business days.
3. Dieselwin
Payout speed: 1-3 business days
Dieselwin lists a payout speed of 1–3 business days.
4. WinBeast
Payout speed: 1-3 business days
WinBeast lists a payout speed of 1–3 business days.
5. Britsino
Payout speed: 1-3 business days
Britsino lists a payout speed of 1–3 business days.
6. Revery Play
Payout speed: 1-3 business days
Revery Play lists a payout speed of 1–3 business days.
7. NightLuck
Payout speed: 1-3 business days
NightLuck lists a payout speed of 1–3 business days.
8. NightWin
Payout speed: 1-3 business days
NightWin lists a payout speed of 1–3 business days.
9. BeOnBet
Payout speed: 1-3 business days
BeOnBet lists a payout speed of 1–3 business days.
10. Chanze
Payout speed: 1-3 business days
Chanze lists a payout speed of 1–3 business days.
“Best” is not a payment feature in its own right. When I assess a casino that accepts direct banking deposits, I look at what the transaction costs and what the cashier says before it is confirmed. A bank-linked option can appear straightforward while the total cost is split across the casino, payment provider and bank. The useful comparison is between the amount leaving the account and the amount credited to the casino balance.
There is no single payment route that can be called the cheapest in every case. A specialist casino-payment review notes that the overall cost can involve a casino charge, a provider fee, a bank or card issuer fee, currency conversion and, where relevant, network costs. Which of these applies depends on the transaction. A cashier’s “no fee” label may cover only the casino’s own charge; it does not necessarily settle what another party may deduct.
That distinction matters most when currencies differ. A conversion spread is the gap between the exchange rate used for the payment and a reference rate. It may be less visible than a fixed fee, but can still affect the amount received. I have seen payment comparisons become misleading when they count only a stated transaction charge and ignore the exchange rate used at checkout. Compare the total, not the headline.
Casinos That Accept Dogecoin in the UK: What to Check
Read the price in context
A direct-banking option should be judged on the terms shown for the actual transaction, not on a general claim that banking is “free”. Before confirming, the relevant details are the currency of the casino account, any fee displayed by the casino or provider, and whether the bank may apply its own charge or conversion. If the cashier does not make a cost clear, that uncertainty is part of the assessment.
The account currency deserves attention before the first payment. A specialist casino review reports that GBP is supported on the pages it examined, but that does not establish the currency setting for every account or every cashier. Confirming the account currency before depositing can prevent an unintended conversion. A UK bank account alone does not prove that the casino balance is held in pounds.
This is not an argument for avoiding a particular method. It is a reason to compare like with like: the same deposit amount, the same account currency and the same payment route. A method with no visible flat charge may still produce a less favourable result after conversion; another may show a fee plainly but leave the exchange rate unchanged. The checkout total is the practical evidence.
Treat “best” as a transaction-level judgement
For best direct-banking casino sites, the meaningful test is whether the cost and currency terms are clear enough to evaluate before payment. A promotional label or a smooth-looking cashier does not answer that. Nor does a general review establish what will appear for a particular account, because payment conditions can vary by provider and transaction.
Cost Assessment
Compare the total amount leaving the bank account against the final amount credited to the casino balance to see the real cost.
My own mistake early on was to treat a listed fee as the whole price. It was only one line of it. The better comparison follows the money through every disclosed charge and checks the currency in which the balance will be credited. If any part of that route is unclear, the site has not made the cost easy to assess. Clarity first.
Checking Whether a Casino Accepts Open Banking
A payment method shown on a casino’s information page is a useful starting point, not proof that it will be available for every account. The cashier is the practical check: it shows which options are currently offered for that account, in that session, before a deposit is made. I have seen the difference between a method appearing in general payment information and being selectable at the point of payment catch people out. The cashier decides.
That distinction matters when looking for a casino that accepts Open Banking. A general page may describe bank-linked payments without confirming that the route is enabled for a particular customer. Availability can depend on the casino’s current payment setup and the account being used. I would check the deposit screen itself rather than treating a review or a site-wide list as a live guarantee. A method that is not presented there is not a usable option for that transaction.
Casinos That Accept E-Checks in the UK: What to Check
Currency needs the same attention. Specialist reviews of casino payment information describe GBP as supported at the sites they cover, but that does not remove the need to confirm the account currency before the first transaction. If the account is set to another currency, a payment can involve conversion; the exchange rate and any resulting cost should not be assumed from a general statement that sterling is supported. The important detail is the currency attached to the individual casino account.
Payment lists also need to be read with care. Specialist reviews may name Visa and Mastercard, but current UK availability and eligibility for a particular card product still need checking in the cashier. UK-licensed casinos cannot accept credit-card payments for gambling, so a brand name on a list does not mean every card carrying that brand can be used. The product type matters. The cashier’s available option, together with the casino’s terms, is more relevant than a broad logo panel.
UK Casino Sites That Accept Debit Cards
I treat the deposit and withdrawal screens as related but separate checks. Seeing a method offered for deposits does not establish that it can also be used to withdraw. The cashier and payment terms should make the applicable route clear; where they do not, the support answer should be obtained before money is moved. That is a compatibility check, not a promise about processing speed.
There is no need to infer acceptance from a casino’s branding or from the phrase “direct banking”. Labels can describe different payment arrangements, and the same wording may not tell how a transaction is made available on a specific site. What matters for a particular account is whether the named bank-linked option appears in the deposit cashier, what currency the account uses, and whether the site explains any conversion or card-product restrictions.
A clean check is deliberately plain: open the cashier, confirm the exact payment option, verify the account currency, and read the conditions attached to that route. If any part is unclear, pause before submitting the deposit. Small checks first.
Payment Verification
- Open the casino cashier
- Confirm the exact payment option is available
- Verify the account currency
- Read the conditions attached to the route
Direct Banking in the UK: Limits and Account Controls
A direct-banking deposit has two separate boundaries: the amount the payment route will process and the amount the casino allows into the account. They can interact, but they are not the same limit. A transfer may be within the casino’s stated maximum and still be declined because a payment-provider or bank control applies.
Specialist casino reviews put the minimum deposit at £10–£20, with the precise entry point depending on the selected method. That range is a guide drawn from published terms, not a fixed rule for every UK direct banking casino. The cashier’s current minimum is the amount that governs a particular transaction; terms can differ between payment routes at the same site.
The upper end is less uniform. Casino terms may set maximums per transaction, per day or per month, and the figures can depend on payment method and account status. A specialist review can offer a snapshot, but it cannot establish the limit for every account or transaction. The amount shown in the cashier and the applicable account terms matter more than a headline figure.
This is where “high limits” can mislead. The phrase may describe a site-level ceiling, not what a payment route will accept in one go or what an individual account can use. A deposit can also be subject to more than one cap. The effective boundary is the one that stops the transaction first. In practice, I treat a displayed maximum as conditional unless the terms make clear whether it applies per payment, across a period, or to the account overall.
Casinos that accept Litecoin in the UK: what to check
There is a separate control that applies before the first deposit. UK Gambling Commission rules require remote gambling licensees to prompt new customers to set a financial limit before they deposit, and to make account-level limit controls accessible. This is not simply another name for a payment method’s maximum. The payment cap is a transaction boundary; the financial limit is an account control intended to let customers manage gambling spend.
That distinction matters when a deposit does not go through. A decline does not, by itself, show which boundary was reached. The payment route may have a cap, the casino may apply an account-level maximum, or a financial limit may prevent further deposits. The cashier or account controls should identify the relevant restriction; where they do not, the operator’s terms or support channel can clarify it.
A UK direct banking casino therefore needs to be assessed on more than the minimum shown beside a deposit button. The useful details are the minimum, the separate maximums, the period each maximum covers, and the way account-level financial controls are presented. Limits are operational terms, not a promise that a particular amount will be accepted. The boundary can differ by account.
How Bank Payments Compare with Other Casino Methods
An Open Banking casino payment method sits between a card payment and a conventional bank transfer: it uses a bank account, but the payment is initiated through a linked service rather than by entering card details. That makes it a distinct route, not simply another name for every bank payment. In practice, the cashier’s options determine whether it is available alongside cards or other methods.
Debit Cards
Commonly accepted via Visa and Mastercard; credit cards are prohibited at UK-licensed casinos.
Apple Pay
Available at some UKGC-licensed casinos as a site-dependent deposit route.
Paysafecard
Prepaid vouchers used for deposits only, not suitable for receiving payouts.
Debit cards remain a familiar alternative. UK casinos commonly accept Visa and Mastercard debit cards, though the presence of a card brand on a general payment page does not establish that every card product will work for every transaction. Credit-card payments for gambling are not permitted at UK-licensed casinos. That distinction matters: “card payments” is not a single category.
Apple Pay is another possible deposit route, with acceptance at some UKGC-licensed casinos. Its role is site-dependent, so it should not be treated as a universal substitute for a bank-linked payment. The practical difference is the instrument presented at checkout; the underlying availability still comes down to the individual cashier.
Paysafecard works differently again. It is a prepaid voucher and is deposit-only, so it does not serve as a complete payment route for both funding an account and receiving a payout. That limitation can make it less interchangeable with direct banking than a payment method that the cashier supports across both sides of an account.
The useful comparison is therefore not a simple ranking of “fastest” or “best.” Bank-linked payments connect the transaction to a bank account; debit cards use card rails; Apple Pay is accepted only at some licensed sites; and Paysafecard is limited to deposits. Each has a different place in the payment mix.
An “instant banking” label describes the deposit route, not necessarily every stage of moving money out. Treating that phrase as a blanket promise is where the comparison goes wrong. The method’s role is specific. Availability is separate.
Casinos That Accept Wirecard in the UK: What to Check
Why a Fast Banking Deposit Does Not Guarantee a Fast Payout
A deposit and a withdrawal travel through different processes. An Open Banking payment may reach a casino account quickly, but that says little about when a withdrawal will be authorised or arrive. The deposit confirms incoming funds; a payout requires the casino to review the request and release it.
A specialist review describes Open Banking services, PayPal and debit cards connected to fast-payout systems as among the quicker withdrawal routes. That comparison concerns the payment method, not the whole time from pressing “withdraw” to seeing funds in a bank account. The casino’s own approval stage comes first, and delivery can then depend on the route used.
I have seen “instant withdrawal” used as if it describes the entire journey. In practice, it may refer to a particular stage or an eligible account, rather than every request. The label is not a timetable.
Approval comes before delivery
Casinos process withdrawals internally before sending them out. The request may need review, and KYC can affect the timing, especially on a first withdrawal when account verification is still being completed. A specialist review notes that first payouts may take longer for this reason. A quick deposit does not remove that check.
This is why the same direct banking casino withdrawal can feel fast at one stage and slow at another. The payment service may be capable of rapid delivery, while the casino is still assessing or approving the request. Until approval is complete, the funds have not entered the bank-payment leg of the journey.
Attention A fast deposit route does not guarantee a fast payout, as withdrawals must first pass through the casino’s internal approval and KYC checks.
The distinction is easy to miss in promotional wording. “Fast” may describe the available method; it does not establish how quickly a particular withdrawal will clear. Conditions attached to the account and the casino’s processing procedures still matter.
Deposit speed is not payout speed
A card deposit can appear immediately, while the payout takes several business days, according to a specialist review. That contrast is not unique to cards: incoming and outgoing transactions are separate operations, with different checks and processing steps.
For an Open Banking casino withdrawal in the UK, the useful comparison is therefore not simply how quickly money can be deposited. The relevant details are whether the casino must approve the request first, whether KYC remains outstanding, and what delivery timing applies after release. An instant deposit is evidence only about the deposit. The payout has its own clock.
Direct Banking and Casinos Outside GamStop
A bank-linked deposit method can appear on a casino that is not part of GamStop, but the payment option says nothing about the site’s regulatory status. “Instant” describes a transaction claim, not a safeguard. I have seen those ideas blurred in marketing; they answer different questions.
For customers in Great Britain, a remote gambling business taking bets must hold a UK Gambling Commission licence, wherever the business is based. A site described as a non-GamStop casino may therefore be operating outside the UK regulatory system. Its willingness to accept a bank payment does not make it an authorised UK casino, nor does it show that its terms or controls are suitable. Check the operator against the Commission’s public register before considering an account.
There is also a practical distinction between choosing a payment route and managing gambling activity. UK-licensed remote operators must ask new customers to establish a financial limit before they make their first deposit. They must also make account-level limit settings available. Those controls apply to the account; a direct-banking facility does not replace them.
Casinos That Accept Bitcoin in the UK: Payment Checks
The label “not on GamStop” can attract people looking for access after self-exclusion. That is precisely when a payment method should not be treated as a workaround or a sign of reassurance. A bank transfer can move money; it cannot establish that a site is regulated in Britain or provide the protections associated with a UKGC-licensed operator.
Different questions. Different controls.
The Payment Trail: Ownership Checks and Returning Funds
A casino payment is not just money arriving and leaving. It also creates a record of where funds came from and who controls the account. In a direct-banking casino, the bank account used for the transaction should belong to the same person named on the gambling account. When those details align, basic ownership checks are less likely to create avoidable friction.
That is not a promise that every payment will pass without review. A mismatch can leave the operator needing to establish who owns the account or why a different route is involved. From the counter, I saw how a detail that seemed minor to a customer could become a question the payments team could not simply ignore. The trail has to make sense.
There is a reason for that scrutiny. UK anti-money laundering rules generally require a payout to go back to the original payment source. This closed-loop approach helps prevent a casino account from being used to move funds between unrelated people or accounts. If an alternative route is proposed, further checks may be needed before it can be accepted.
The cleanest arrangement is often one named bank account, used consistently for deposits and withdrawals, with matching account details throughout. That does not remove the operator’s obligations or rule out checks; it simply keeps ownership information coherent. A direct banking casino may make the bank connection straightforward, but the payment trail still depends on the account holder being identifiable.
“Seamless” is the sales word. Behind it sits a control: the money should return to the person and source it came from. That is the point.
Why can a fast-payout casino still delay my withdrawal?
A quick payment method does not bypass the casino’s internal approval or verification checks. First withdrawals can take longer while your account is verified, and bank or provider processing can add time too.
Why must withdrawals return to the deposit method?
Returning funds to the original payment source is a common UK anti-fraud and anti-money-laundering control. Using a different route may require extra verification.
Which payment methods are accepted in Great Britain?
UK casinos commonly accept debit cards such as Visa and Mastercard, and may offer bank transfers, Open Banking, PayPal, Skrill, Neteller, Paysafecard and Apple Pay. Availability varies by casino, so check its cashier; Paysafecard is for deposits only.
What is the current minimum deposit?
The minimum is usually £10–£20, depending on the payment method.
Which method has the lowest fees?
There is no universal lowest-fee method. Compare the casino’s charges, provider or bank fees, currency-conversion spread and any network costs for your payment.
Are Visa and Mastercard deposits definitely debit cards?
No. UK casinos commonly accept Visa and Mastercard debit cards, but the card products eligible for deposits can vary. Check the cashier, and note that credit-card gambling has been banned in the UK since 14 April 2020.
Material created by the team Golden Mister