
Card eligibility, deposit limits, payment routes and withdrawal processing can all affect how debit cards work at UK casinos.
How Debit Cards Fit into UK Casino Payments
Debit cards sit at the familiar end of the payment menu. UK casinos commonly accept Visa and Mastercard debit cards, so a card already used for everyday banking can also be a straightforward way to fund a casino account. The transaction begins through the casino’s cashier: the player selects the card option, enters the payment details and confirms the deposit through the bank’s security process. The casino then records the funds in the account.
That familiarity explains why cards remain prominent even as cashiers have added other routes. They connect a casino deposit to a bank account without requiring a separate e-wallet balance or a prepaid voucher. From the operator’s side, cards are also a recognisable payment category with established processing arrangements. Still, a payment menu is not a promise that every customer’s card will work at every site. The menu is best understood as a range of routes, each with its own practical characteristics.
A card is not the only way to move money into an account. PayPal, bank transfers, open banking services, e-wallets, mobile wallets and prepaid options may appear alongside card payments, depending on the casino. Their presence broadens the payment picture; it does not make them interchangeable. Some are designed around a bank account, some hold a separate balance, and some provide a deposit route without being available for withdrawals. The distinction matters before any method is treated as a complete account-payment solution.
A specialist review describes PayPal as popular for speed and convenience, while noting that a casino’s bonus terms may exclude deposits made through it. That is a reminder that a payment method can work perfectly well for funding an account yet receive different treatment under a promotion. The bonus rules and the payment rules are separate layers. The cashier explains how to pay; the promotion terms explain which deposits qualify.
Skrill and Neteller are also offered at some sites. A specialist review notes that these e-wallets are often excluded from promotions, so their usefulness depends partly on whether a player values keeping money in a separate online balance or wants to use a particular offer. There is no universal advantage in choosing an e-wallet simply because it is listed. The payment route should fit the intended use of the account.
Casino sites that accept EcoPayz in the UK: how to check
Open banking and bank transfers form another part of the landscape. A specialist review reports that these routes can provide instant deposits and fast withdrawals at many sites, but availability and performance are specific to the operator and service involved. Bank transfers are familiar to people who prefer a direct bank-to-merchant route, while open banking services connect through a bank account using a digital payment flow. These are alternatives to a debit-card transaction, not names for the same process.
Prepaid payments work differently again. Paysafecard is a voucher for deposits only, which makes it distinct from methods that may also support withdrawals. A deposit-only route can still suit someone who wants to separate a payment from their main card details, but it does not provide a route for cashing out. That limitation is structural, not a temporary delay.
Some UKGC-licensed casinos also accept Apple Pay for deposits. It can provide a mobile-wallet route linked to a payment card, but its appearance in a cashier should not be taken to mean it is available for every account or transaction. The same principle applies across the wider menu: payment names indicate possible routes, while the operator’s terms and cashier define what is actually offered.
I have seen payment menus treated as if a longer list automatically means a better experience. It does not. A card may be the simplest option for someone who wants to pay from a bank account directly; an e-wallet may suit someone who already uses one; a prepaid voucher may be relevant where deposit-only access is enough. These are differences in how the account is funded, not a ranking of casinos or payment methods.
For UK players, the wider context is that real-money online gambling is legal at sites operating under the relevant UK Gambling Commission licence. Payment choice does not replace that basic regulatory condition. Nor does the presence of a debit-card logo, by itself, establish that every feature of an account is suitable. A payment menu is one part of the service.
The sensible starting point is therefore simple: debit cards are a common funding route, but they belong to a broader system of cards, bank-linked services, wallets and prepaid methods. Each route has a different role. Familiarity matters. So does fit.
Which Casinos Accept Debit Cards—and What to Check
When choosing a UK casino that accepts debit cards, it is worth checking the available payout information as well as the payment options. The details below provide a concise point of reference for the listed sites.
1. Zombillion
Payout speed: 1-3 business days
Zombillion has a stated payout speed of 1–3 business days.
2. SlotoSport
Payout speed: 1-3 business days
SlotoSport has a stated payout speed of 1–3 business days.
3. Dieselwin
Payout speed: 1-3 business days
Dieselwin has a stated payout speed of 1–3 business days.
4. WinBeast
Payout speed: 1-3 business days
WinBeast has a stated payout speed of 1–3 business days.
5. Britsino
Payout speed: 1-3 business days
Britsino has a stated payout speed of 1–3 business days.
6. Revery Play
Payout speed: 1-3 business days
Revery Play has a stated payout speed of 1–3 business days.
7. NightLuck
Payout speed: 1-3 business days
NightLuck has a stated payout speed of 1–3 business days.
8. NightWin
Payout speed: 1-3 business days
NightWin has a stated payout speed of 1–3 business days.
9. BeOnBet
Payout speed: 1-3 business days
BeOnBet has a stated payout speed of 1–3 business days.
10. Chanze
Payout speed: 1-3 business days
Chanze has a stated payout speed of 1–3 business days.
Debit cards are a common way to fund UK casino accounts, but a general claim that a casino accepts cards does not confirm that a particular deposit will work. The useful question is narrower: does the casino currently offer card deposits to UK customers, and does its cashier accept the specific card product being used?
I treat a payment-method page as a starting point, not a final answer. A specialist review may list Visa and Mastercard, but availability can change and a network logo does not establish that every card on that network is eligible. The cashier is the practical check because it shows the methods the operator currently makes available for that account and transaction.
Check the cashier, not just the homepage
A casino’s homepage may display payment logos for recognition, or a general payments page may describe methods without showing whether they are enabled for a particular customer. Those details can be out of date or incomplete. The cashier is closer to the actual deposit process: it identifies the payment options the site presents when an account is ready to make a deposit.
Before choosing a casino, look for its payment information and then confirm the card option in the cashier. Check that the method is presented for deposits, rather than assuming that a logo means it can be used for every payment function. If the cashier is unavailable before registration, the operator’s help pages or customer support may clarify the current position; the answer should still be checked against the cashier before attempting to pay.
Casinos That Accept Debit Cards in the UK
A familiar network name is only part of the test. A debit card may be issued under Visa or Mastercard while the issuer, card type or account setup affects whether a particular transaction is accepted. The cashier may also present card options differently after an account has been created. A generic statement such as “cards accepted” therefore leaves an important detail unresolved: which card products can be used in the current deposit flow?
Read the wording precisely
Payment pages sometimes use broad labels such as “bank cards”. That wording can describe a category without confirming the status of every card in it. Look for an explicit debit-card option, or a clear explanation of which card types the operator accepts. Where the page names a network but does not distinguish debit from other card products, do not infer eligibility from the logo alone.
There is a practical difference between a method being mentioned and being available. A method can appear in general information while not being offered in the cashier for a particular account. It may also be temporarily unavailable. That is why a review or payment guide can help identify what to investigate, but it cannot replace the live payment screen.
Do
- Check the cashier for current card availability
- Read precise wording for debit card eligibility
- Confirm the operator’s UKGC license status
Don’t
- Rely on homepage logos as final confirmation
- Infer eligibility from broad labels like “bank cards”
- Assume a successful payment proves site authorization
When the cashier does show a card option, read the associated instructions before proceeding. The stated requirements may identify the card types supported or explain what to do if a transaction is declined. If the wording is unclear, a direct question to the operator is more useful than relying on a broad promotional claim. Keep the response specific: whether debit-card deposits are currently available to UK customers and whether the particular card product is eligible.
Confirm the operator and account context
A payment method is not a substitute for checking who runs the casino. For legal online gambling in Great Britain, the remote gambling licensee must hold the relevant UK Gambling Commission licence. The licence number can be checked on the Commission’s public register. A card logo says nothing about licensing status, and a successful payment would not establish that the site is authorised to serve the market.
There is also an account-stage distinction. UK-licensed operators must verify a customer’s age before allowing a deposit. As a result, the cashier may not be ready to accept funds until the required account checks have been completed. That is part of the operator’s process, not evidence that the card method is unsupported. If an option is absent, the reason should be clarified rather than guessed.
I separate three checks: whether the operator is properly licensed, whether card deposits are currently offered, and whether the actual card product is accepted. Combining them into one assumption is how avoidable confusion starts. A casino may be licensed while a particular card is not eligible; a card logo may be visible while the method is not enabled in the current cashier.
The most dependable confirmation is therefore specific and current: the operator is listed on the regulator’s register, its payment information identifies card deposits, and the cashier presents the option for the account. If any part remains ambiguous, pause before entering payment details and ask the operator to confirm. The distinction is small. It matters.
UK Casino Sites That Accept Jeton: What to Check
Comparing Debit Card Payment Costs and Account Currency
A debit card cannot be called the cheapest casino payment method without looking at the transaction behind the claim. The total may depend on charges from the casino, the payment provider, the card issuer or bank, currency conversion and network costs. A specialist payment review identifies these as separate parts of the calculation; none should be treated as a charge that applies to every card deposit.
I compare the full route, not a label such as “fee-free”. That wording may mean the casino does not add a charge. It does not, by itself, establish that the provider or bank adds nothing, or that a currency conversion is being made at a neutral rate. The relevant terms are those attached to the particular account, card and transaction.
Start with the account currency
Before making a payment, establish the currency in which the casino account is held. Specialist review pages report GBP as a supported currency at the sites they cover, but that is not a reason to assume every account is set up in pounds. The account currency should be confirmed before the first transaction.
When the card account and casino balance use different currencies, conversion may enter the calculation. It can happen at a point in the payment route that is not obvious from the deposit screen. The displayed amount might be in pounds while the card issuer later records a converted amount, or the casino may hold the account in another currency. The important detail is which party converts the funds and what rate it applies.
A conversion spread is the difference between a reference exchange rate and the rate used for the transaction. A specialist payment review warns that this spread can cost more than a visible flat fee. That is why a payment with no separately stated charge is not necessarily the least expensive. The exchange rate can carry a cost of its own.
Read the charge terms as a chain
The payment route has several possible points where a cost can appear. A casino may state its own deposit charges; a provider may have separate terms; a bank or card issuer may apply charges under the card account; and currency conversion or network costs may also matter. A charge at one point does not tell the whole story.
Casinos That Accept Wirecard in the UK: What to Check
In practice, I would record each disclosed cost against the transaction it relates to. The amount sent, the amount credited to the casino balance and the amount ultimately charged to the card are useful checkpoints. If those figures do not match, the difference needs an explanation: a fee, a conversion, or another adjustment in the route. Without that reconciliation, “no fee” is only a partial description.
The same comparison should be made against the actual amount intended for deposit. A flat charge has a different effect from a percentage-based cost, while an exchange-rate spread changes with the conversion. A specialist payment review advises comparing casino charges, provider fees, currency spread and network cost for the amount being considered. There is no universal lowest-fee method that can be declared cheapest independently of those details.
This is also why a comparison between a debit card and another payment route needs more than a headline fee. The other route may involve a different provider, currency handling or bank charge. Comparing one method’s visible casino charge with another method’s total cost is not like-for-like. The terms need to be checked at each relevant stage.
Keep the evidence specific
The cashier and the casino’s payment terms can show which charges the operator discloses, but they may not describe every cost imposed by a bank or card issuer. Those terms belong to the relevant financial provider. I treat an advertised “free” deposit as a statement about the charge named in the offer, not as proof that every part of the route is costless.
A sound comparison therefore has three checks: the casino account currency, the conversion rate and responsibility, and the fees disclosed by each party in the payment chain. If the account is in GBP and the card is charged in GBP, that removes one obvious currency mismatch, though it does not establish that no other charge applies. If currencies differ, the conversion point and rate deserve particular attention.
A payment with no separately stated charge is not necessarily the least expensive, as the exchange rate spread can carry its own cost.
There is no useful shortcut in choosing a payment method by reputation. The cheapest route is the one whose full cost is clear for the specific transaction, once casino, provider, bank or issuer, conversion and network charges have been considered. That is the calculation that matters.
What Happens Between a Debit Card Deposit and a Payout
A debit-card payment has two separate journeys. Money going into a casino account is authorised through the card payment route; money coming out is subject to the casino’s checks and the rules governing where gambling funds can be returned. A successful deposit therefore confirms only that the incoming transaction was accepted. It does not mean a later withdrawal will follow the same steps in reverse or arrive at the same speed.
The distinction is easy to miss in a cashier that presents deposit and withdrawal options side by side. Behind that display, the operator has to identify the source of funds, review the account and decide which payout route is permitted. The method shown for adding money is not necessarily a promise that every withdrawal can be sent through an alternative chosen later.
Why payouts are linked to the deposit source
UK anti-money laundering requirements generally mean that a payout should return to the original payment source. This is part of the closed-loop rules: funds are not simply sent wherever an account holder asks. Returning money along the route used to fund the account helps the casino check that the payment belongs to the customer and is not being used to move funds between unrelated accounts.
In practical terms, a debit-card deposit can create an expectation that the card will be involved when funds leave the casino account. The card may not behave like a bank account that can receive an ordinary incoming transfer, so the operator’s cashier may explain how a card payout is handled or show another route for the final payment. That detail depends on the operator’s process and the payment facilities available. The important point is that a different option in the cashier does not automatically override the original-source requirement.
Casinos That Accept Bitcoin in the UK: Payment Checks
If the casino proposes an alternative route, the reason matters. It may need further checks to establish that the destination belongs to the same customer and that the payout remains consistent with its controls. That can mean an additional request for information rather than an immediate transfer. A payout route is part of the account’s payment history, not just a preference selected at the last moment.
What the operator checks before release
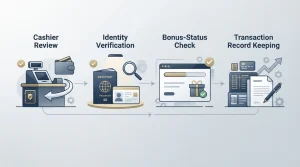
A withdrawal request is not necessarily transmitted to the payment provider as soon as it is submitted. The casino may first review the account and approve the request internally. The payment then has to pass through the relevant payment channel. These are distinct stages, and an account screen may not make the distinction obvious.
A specialist review describes withdrawal processing as including the casino’s own approval, with first withdrawals potentially taking longer while verification is completed. That is a description from a review, not a timetable that applies to every debit-card casino. The operator’s terms and the account’s status determine what happens in an individual case.
KYC is closely connected to this stage. If identity or payment ownership checks are still outstanding, the operator may need to resolve them before approving a payout. A request can therefore be waiting with the casino even though the card itself was accepted without difficulty for the deposit. That difference is procedural: the incoming payment and the outgoing payment are assessed for different purposes.
The cleanest transaction record is one in which the account details and payment route belong to the same customer. Where details do not align, the operator may have to ask for clarification before it can confidently release funds. This is not necessarily a sign that the payment has failed; it may mean the review has not yet reached the point where the payout can be sent.
Why the two directions can take different time
A card deposit may be authorised quickly, while a withdrawal involves internal review followed by payment-provider handling. A specialist review reports that a card deposit can be instant even where a payout takes several business days. That example should not be read as a guaranteed schedule: the operator’s approval process, verification status and payment route all affect the outcome.
Casinos That Accept Instadebit in the UK: What to Check
From the inside, the useful distinction is between “requested”, “approved” and “sent”. A withdrawal shown as requested may still be in the casino’s queue. Once approved, it may need to be passed to the payment provider, whose handling is separate from the casino’s own decision. A status update at one stage does not establish that the money has reached the card or bank account.
For a debit-card casino, the deposit is only the beginning of the payment record. The payout follows the operator’s checks and the source-linked route, rather than simply repeating the speed of the original card authorisation. That is the mechanics behind the delay.
Can a Debit Card Be Used for Online Gambling in the UK?
A debit card can be used to fund an online gambling account at a casino that accepts it. The important distinction is where the money comes from: a debit transaction draws on funds in a bank account, while a credit-card payment borrows against a credit facility. They may look similar in a cashier, but they are not treated alike for gambling.
For UK-licensed casinos, credit-card payments for gambling are prohibited. The regulator introduced the ban on 14 April 2020, and it remains in force. I have seen the distinction blurred in payment descriptions, especially where a card is presented as one option among several. The label does not change the underlying funding source.
The restriction also covers attempts to route credit-card funds through an intermediary. A payment cannot be made acceptable simply by passing it through a money service business first. Nor can a casino accept a wallet payment where that wallet allows credit-card funds to be used for gambling. These rules close off routes that would otherwise make the ban easy to sidestep.
That is why “card accepted” is not enough to establish that every card payment is permitted. The relevant question is whether the transaction is funded from a debit balance or from credit. A debit card linked to a customer’s bank account is different from a credit card, even when both carry familiar card-network branding.
Credit Card Ban
Credit-card payments for gambling are prohibited for UK-licensed casinos, including routes attempting to use intermediaries to sidestep the ban.
I have found that the cleanest explanation is the least complicated one: debit means spending money held in the account; credit means borrowing. A casino’s payment controls should reflect that difference, rather than relying on the appearance of the card or the name of an intermediary. No workaround.
The prohibition is about credit-card gambling, not about debit-card deposits. It does not make every casino or every payment route suitable by itself. In the UK, real-money online gambling is lawful only through a site holding the appropriate local licence; a debit card does not confer that status. The payment type and the operator’s regulatory position are separate checks.
So, yes: a debit card may be used for online gambling where the casino permits it and the payment is genuinely debit-funded. Credit-card payments for gambling remain barred, including credit-funded routes disguised as another method. The distinction is functional, not cosmetic.
Deposit Minimums and Limits to Check Before Paying
A debit-card deposit can be accepted while still falling below a casino’s minimum. The cashier sets the operative threshold, and it may differ from the amount shown in general payment information. A specialist casino review reports starting minimums in the £10–£20 range, with the figure depending on the payment method. That is a reported range, not a standard that applies to every site or every card.
Casinos That Accept iDEAL in the UK: What to Check
The distinction matters at the point of entry. A minimum is the smallest payment the cashier will process; it does not describe the maximum allowed or the amount that can be deposited over time. Where a card option is listed, the payment screen is the practical place to check the current floor before entering an amount. Conditions can differ between payment routes within the same account.
Maximums may be set per transaction, per day or per month. A specialist casino review describes these caps as varying by payment method and account status. Account-level controls can also affect what is available. An established account and one still subject to checks may not have identical transaction permissions, so a limit quoted in a general guide should not be treated as a personal allowance.
There is another limit to distinguish from the cashier’s payment cap: the customer’s own financial limit. UKGC rules require remote gambling licensees to prompt new customers to set a financial limit before their first deposit and to make account-level limit controls accessible. This is not the same as the payment method’s minimum or maximum. One controls spending at account level; the other determines what a payment channel will accept.
From inside the operation, these figures are easy to blur in promotional copy. “Low minimum” describes an entry threshold, not a promise that every card transaction will be accepted at that amount. A declined or blocked payment can reflect a separate account or payment control.
Check both layers before funding: the amount the cashier accepts for that transaction and the financial limit recorded on the account. Then the deposit amount is clear. No guesswork.
Deposit Limits Check
- Verify the minimum deposit amount in the cashier
- Check for per-transaction, daily, or monthly maximums
- Set a personal financial limit on the account
Why a Fast Card Deposit Does Not Guarantee a Fast Withdrawal
A debit-card deposit and a withdrawal are separate stages, handled by different checks. A card payment may appear in the casino balance quickly, so play slots with a debit card can begin without waiting for a payout-style review. That speed says little about how soon money will leave the account.
From the operator’s side, a withdrawal is not simply a reversed deposit. The casino must approve the request, and it may need to finish KYC before releasing funds. A first withdrawal can take longer if identity or account checks are still outstanding. In my experience, the key distinction is between money being authorised for play and a payout being cleared for release. Different queues. Different controls.
The payment route matters too. A specialist review describes PayPal, open banking services and debit cards connected to fast payout systems as options that can be among the quicker withdrawal routes. That is not a promise that every casino supports each route, or that a card payout will be quick at a particular site. The operator’s processing stage still comes first; the payment provider’s own handling follows.
This is why “instant” can be accurate for a deposit and misleading when applied to the whole account. A fast card authorisation confirms that funds can be added. It does not confirm that the account is fully verified, that a withdrawal has been approved, or that the chosen payout route will complete immediately. A specialist review notes that a card deposit may be instant while a payout takes several business days; the actual timing depends on the casino and payment route.
I would treat a stated withdrawal speed as a description of the payment method under the operator’s process, not as a countdown from the moment a withdrawal is requested. If the account is already verified and the casino supports a fast payout system linked to the card, the route may be quicker. If approval or KYC remains, the faster payment rail cannot remove that delay. The deposit clock is not the withdrawal clock.
Debit Cards at Non-Gamstop Casinos: Check the Licence and Controls
A debit-card option does not establish that a casino is licensed to serve customers in Great Britain. “Non-Gamstop” describes a site’s relationship with the self-exclusion scheme; it is not a regulatory category or a quality mark. I treat the payment logo and the licence as separate checks.
Casinos That Accept Upaycard in the UK: What to Check
Remote gambling licensees serving Great Britain must hold the relevant UK Gambling Commission licence, wherever the business is based. A casino operating outside that system does not have a UKGC licence. That distinction matters: online gambling in the UK is legal only through licensed and regulated sites. A familiar cashier or a working card payment cannot change the operator’s regulatory status.
The practical check is the UKGC public register. The operator’s legal name and licence details should match the register, rather than simply appearing in a footer or promotional badge. A mismatch, missing details or a licence belonging to a different business is a reason to stop and establish who is actually providing the gambling service. A card accepted at checkout proves only that the transaction route is available.
Account controls are another useful test of how a licensed service is meant to operate. UKGC rules require remote operators to ask new customers to choose a financial limit before their first deposit, and to make account-level limit settings accessible. These are safeguards built into the regulated customer journey, not optional features that a debit card supplies.
I would not treat the phrase “non-Gamstop” as shorthand for greater freedom without checking what sits behind it. A site outside the UKGC system does not have the same UK regulatory oversight or the same required account protections. The distinction is material.
Separate the questions. Is the casino authorised for the British market? Are its account controls clear and usable? Does the cashier accept the particular debit card? The last answer says nothing about the first two. Payment compatibility is not a licence.
Visa Debit Cards and Other Card Eligibility Checks
Visa and Mastercard are commonly accepted debit-card networks at UK casinos, but a logo on a payment page is not confirmation that every card carrying it will work. I have seen the distinction cause avoidable confusion: network acceptance describes the route in general, while the cashier determines whether a particular product is available for that account and transaction.
A specialist review lists Visa and Mastercard among the payment methods offered by the sites it examined. That is useful as an indication of what may be supported, not a standing guarantee of current UK availability. Payment options can differ between operators, and the cashier is the practical check before relying on a card.
The important detail is the card product, not just the network name. A Visa debit card and a Mastercard debit card may both be listed, while a particular card or account is not eligible for the casino’s payment flow. The cashier’s displayed options and any instructions attached to them are more relevant than a general claim that the casino accepts Visa or Mastercard.
I treat the payment screen as the final confirmation: check that the intended network appears, that the card is being handled as debit, and that the available option applies to the account being used. If the cashier does not show the method, a logo elsewhere on the site does not establish that it can be used at that moment. Details matter.
Joining with a Debit Card: Keep the Payment Route Consistent
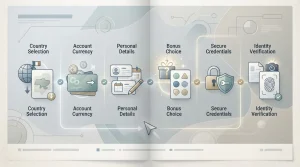
When opening a casino account, the details entered at registration become the reference point for later payment checks. A debit card in the account holder’s own name, used with matching account information, keeps basic ownership details aligned. A mismatch can prompt questions or delay a transaction even when the card itself is accepted.
I have seen payment checks become harder to resolve when a player registers under one name but tries to pay through an account belonging to someone else. The issue is not simply whether a deposit goes through. Remote gambling licensees need to establish who owns the account and the payment route, and inconsistent details can make that harder to confirm.
The cleanest arrangement is often one named account used consistently for both deposits and withdrawals. That gives the casino a clearer record of where funds came from and where they should be returned under closed-loop rules. Switching between payment accounts, or using another person’s card, can create avoidable friction when ownership has to be checked.
Before funding a new account, the registration details and debit-card details should therefore agree. Names, account ownership and the selected payment route matter more than trying to move between several sources. A card being visible in a cashier does not resolve an ownership mismatch.
This is a practical check, not a shortcut around KYC. A casino may still ask for documents or further information to verify an account. Keeping the details consistent simply avoids adding a preventable complication at the joining stage.
Fewer loose ends.
Why can a fast payout casino still delay my withdrawal?
A fast payout method does not bypass the casino’s internal approval process. First withdrawals can take longer if verification is still being completed.
Are Visa and Mastercard deposits definitely debit cards?
No. A Visa or Mastercard logo does not confirm that every card product is eligible; check the casino’s cashier for the card options available to you.
Why must withdrawals return to the deposit method?
Returning funds to the original payment source is a common anti-fraud and anti-money-laundering control. Using another route may require additional verification.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest. The casino’s approval process and your verification status also affect how quickly you receive the money.
Do UK casino withdrawals require verification?
Verification may be needed, particularly before a first withdrawal. Delays can occur while the casino completes those checks.
What is the current minimum deposit?
Minimum deposits usually start at £10–£20, depending on the payment method.
Can I deposit in GBP?
Yes, GBP is supported. Check your account currency before your first transaction to avoid conversion.
Material created by the team Golden Mister