
Voucher alternatives differ in how they are funded, and a cashier listing alone may not confirm whether a method supports withdrawals.
What Can Replace a Ukash Deposit?
There is no single substitute that behaves exactly like a prepaid voucher. The practical alternatives at UK casinos fall into different groups: debit cards, online banking routes, e-wallets and other prepaid products. Each changes how a deposit is funded, and a method that appears familiar on a cashier is not automatically equivalent in how it can be used.
Debit cards are the most straightforward comparison. UK casinos commonly accept Visa and Mastercard debit cards, so the money comes from a bank account rather than from a voucher balance. Credit-card payments for gambling are not permitted at UK-licensed casinos; that restriction also covers credit-card funds routed through a money service business. The distinction matters when choosing a card or a wallet linked to one. A payment route should not be treated as acceptable simply because its screen shows a card brand.
A card is familiar, but it is not prepaid in the same sense as a voucher. The deposit is charged through the linked bank account, and the casino may ask for payment details that match the account holder. In my experience, this is where a seemingly simple alternative becomes a question of account ownership and payment method, rather than just whether the deposit button works. Familiar does not mean identical.
When looking for casinos that accept Ukash in the UK in 2026, check the available payment methods directly, as they can change. The details below provide a concise reference to the payout timing known for each operator.
1. Zombillion
Payout speed: 1-3 business days
Zombillion lists a payout speed of 1–3 business days.
2. SlotoSport
Payout speed: 1-3 business days
SlotoSport lists a payout speed of 1–3 business days.
3. Dieselwin
Payout speed: 1-3 business days
Dieselwin lists a payout speed of 1–3 business days.
4. WinBeast
Payout speed: 1-3 business days
WinBeast lists a payout speed of 1–3 business days.
5. Britsino
Payout speed: 1-3 business days
Britsino lists a payout speed of 1–3 business days.
6. Revery Play
Payout speed: 1-3 business days
Revery Play lists a payout speed of 1–3 business days.
7. NightLuck
Payout speed: 1-3 business days
NightLuck lists a payout speed of 1–3 business days.
8. NightWin
Payout speed: 1-3 business days
NightWin lists a payout speed of 1–3 business days.
9. BeOnBet
Payout speed: 1-3 business days
BeOnBet lists a payout speed of 1–3 business days.
10. Chanze
Payout speed: 1-3 business days
Chanze lists a payout speed of 1–3 business days.
PayPal offers a different kind of route: an online account used to make payments without entering card details at the casino each time. A specialist review describes it as popular for speed and convenience, while also noting that it may be excluded from bonus eligibility. That qualification is important. A payment method and a promotion are separate parts of the transaction, and a deposit made through one route should not be assumed to qualify for an offer. The terms attached to a particular promotion decide that point.
Open banking and bank transfers are another alternative. A specialist review reports that these can provide instant deposits and fast withdrawals at many sites. The important practical difference from a voucher is that the payment is linked to a bank account and its banking process, rather than being made from a prepaid code. For someone comparing routes, the relevant question is not simply which one feels quickest at the deposit stage; the whole payment journey can involve different checks and processing.
Casinos That Accept E-Checks in the UK: What to Check
Prepaid vouchers remain the closest category in form, because funds are loaded onto a voucher before being used. Paysafecard is a deposit-only option. That makes it relevant when the priority is to pay in through a prepaid product, but it should not be mistaken for a complete deposit-and-payout route. Its role is narrower than a general-purpose payment account. A voucher can therefore resemble the way a person thinks about a Ukash deposit without reproducing every function they may expect from it.
E-wallets sit between bank-linked payments and prepaid products. Skrill and Neteller are available at some sites, according to a specialist review, which also reports that they are often excluded from promotions. They are account-based payment services, not vouchers. Their presence can provide another way to fund an account, but promotional eligibility needs to be read separately rather than inferred from the cashier listing. A method can be accepted for deposits and still be treated differently under bonus terms.
UK Casinos That Accept E-Wallets: Payment Guide
The label “best” is doing too much work when the routes serve different needs. A debit card may suit someone who wants to use an existing bank card; an e-wallet may suit someone who prefers a separate payment account; a prepaid voucher may suit someone looking for deposit-only spending. Open banking or a bank transfer may appeal where a direct bank route is preferred. None of those descriptions guarantees that a specific casino offers the route or that its terms will fit a particular promotion.
Bonus-led choices need particular care. A casino’s payment options and its bonus conditions are not the same list. PayPal, Skrill and Neteller have been reported by specialist reviews as methods that may be excluded from promotions, but the treatment can vary by offer. A “bonus alternative” is therefore not a separate payment product: it is a payment route whose eligibility has to be checked against the offer’s wording. The same applies to no-deposit promotions, which do not become available merely because a different deposit method is chosen.
Do
- Check a payment route’s eligibility against the specific offer’s wording
- Verify if a deposit method is excluded from bonus eligibility
Don’t
- Assume a deposit method automatically qualifies for a promotion
- Treat a payment route as a “bonus alternative” without checking terms
In short, alternatives exist across several payment categories, but they are not interchangeable. The useful comparison is between how each route is funded and what the relevant casino and promotion permit—not whether its name sounds like a direct replacement.
What the UK Casino Cashier Actually Shows
A casino’s general payment page is a directory, not a live record of what can be used on a particular account. It may name familiar brands or describe broad payment categories, but that does not establish that every listed method is available to a UK customer at the point of deposit. The cashier is where the practical answer appears: which methods can be selected, what the account is eligible to use and what the transaction screen requires.
That distinction matters when checking for Ukash. A payment logo on a site page, or a general statement about prepaid deposits, is not confirmation that a Ukash transaction can be made. Nor does a cashier that offers other payment routes settle the wider question of Ukash’s status. These are separate checks: one concerns what a specific account can select now; the other concerns whether the named product itself is accepted.
I treat the cashier as the operational source because it sits closer to the transaction than promotional or overview copy. A specialist review may list Visa and Mastercard and state that GBP is supported, but those details still need checking against the live account. For cards, current UK availability and the eligibility of the particular card product must be confirmed in the cashier. UK-licensed casinos cannot accept credit-card payments for gambling, so the presence of a card brand does not mean that every card carrying its name can be used.
Casinos That Accept Upaycard in the UK: What to Check
The steps are straightforward, but the details are easy to overlook. The deposit screen may show the methods available to that account, while selecting one may reveal further conditions or prompt for information. A method described elsewhere on the site may not appear there. Conversely, seeing a method in a general list does not prove it is selectable for that transaction. The cashier is not a promise; it is the point at which a payment route becomes testable.
Currency deserves the same attention. A specialist review may report that a casino page supports GBP, but the account currency should still be confirmed before the first transaction. If the account is set to another currency, a deposit may involve conversion rather than being processed in pounds. That can affect what is debited or credited, even when the payment method itself is available. The account setting is therefore part of the payment check, not a minor display preference.
There is also a difference between a method being visible and a deposit being permitted. Remote gambling operators must verify a customer’s age before allowing a deposit, and UKGC-licensed operators must prompt new customers to set a financial limit before their first deposit. Those controls are part of the account process; they do not indicate that a particular payment brand is supported. A cashier can show a route while the account still has steps to complete.
From the operator’s side, payment information is often spread across several places: a general payments page, terms, help material and the cashier. They serve different purposes. Overview pages explain what the business lists; terms set conditions; the cashier reflects the options presented for the account. When the wording differs, the live transaction screen is the useful place to verify availability, while any linked conditions explain how that option works.
Verify Payment Availability
Check the Cashier
Identify which payment methods are selectable for your specific account on the live transaction screen.
Confirm Currency
Verify that the account currency is set to GBP to avoid potential conversion issues.
Review Conditions
Check for any account-level requirements, such as age verification or financial limits, before depositing.
A careful check records the method name as displayed, the currency shown on the account and any conditions attached before confirming a deposit. It also avoids treating a logo as evidence that a payment will work for every customer or every card product. Small distinctions matter. Especially at the point of payment.
This practical method check should not be mistaken for proof that Ukash is accepted, or proof that it is not. It answers a narrower question: what does this UK casino cashier currently offer to this account? Anything broader needs separate confirmation.
Can a Prepaid Deposit Also Pay Out?
A deposit method and a withdrawal method are not automatically the same thing. A prepaid payment can appear suitable for adding funds, yet that does not establish that the casino can send a later payout back through it. The distinction matters because a casino must account for where money came from as well as where it is going.
UK anti-money laundering rules usually require winnings and returned funds to go back to the original payment source. This is part of the closed-loop approach: a deposit is linked to its source, and a payout is not treated as an entirely separate transaction. If that source cannot receive money, the casino may need to identify another permitted route and carry out additional checks.
That is why a prepaid deposit should not be treated as a promise of a prepaid withdrawal. The word “accepted” can describe only the deposit side of the cashier. It does not, by itself, tell the whole story about paying out. The distinction is easy to miss when a payment option is presented as a single logo or name.
Casinos That Accept USDC in the UK: What to Check
With a Ukash-labelled payment in mind, the practical question is not simply whether funds could be put into an account. The payout route would also have to be established for that exact method and transaction. A name associated with a deposit does not prove that a casino can return funds to it. Nor does a successful deposit settle how a future withdrawal will be handled.
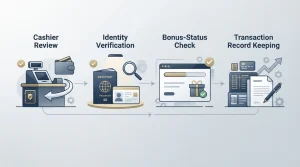
In operational terms, the payment record matters. The casino needs to connect the account holder, the deposit source and the destination for the payout. When those details line up, the transaction is easier to process. When the original source cannot accept a return, the casino may ask for another route or for further verification before releasing funds. That is a control, not necessarily a sign that the deposit itself failed.
I have seen the difference between a payment button and a working payout route become important only after a withdrawal was requested. A cashier may make a deposit choice look self-contained, while the back-office process has to apply rules about ownership and return of funds. The screen is only one part of the transaction.
First withdrawals can involve an additional pause while account verification is completed. A specialist casino review describes processing time as including the operator’s internal approval, with first withdrawals potentially taking longer during verification. That is a description of a review’s account, not a fixed timetable for every casino or payment route. The casino’s own terms and account checks determine what happens in a particular case.
Payout Risks
UK anti-money laundering rules typically require winnings to return to the original payment source; if a prepaid source cannot receive funds, alternative verification is required.
This also means that a deposit arriving quickly does not establish how quickly a payout will be approved or delivered. Deposit processing and withdrawal processing are separate stages. The second may require the casino to confirm identity, ownership and the appropriate destination before money leaves the account.
For a player considering whether a Ukash deposit can be used at an online casino, the sensible distinction is between funding an account and completing the full deposit-to-payout path. The same principle applies whether the balance is intended for slots or live casino games: the game type does not alter the source-return mechanics. Mobile access does not change them either.
The key point is narrow but important: a payment method’s deposit role cannot be assumed to include withdrawals. A casino may need to return funds to the original source under anti-money laundering controls, and an unavailable return route can lead to an alternative process and more checks. The payment method must make sense at both ends of the transaction.
No shortcut.
Ukash Casinos in the UK: What Can Be Confirmed
A list of casinos said to accept Ukash is only useful if the payment method can be confirmed for the account and transaction in question. A name on an old comparison page, a general payment logo or a copied list does not establish that a UK player can make a Ukash deposit there now. I would not treat an operator as a confirmed Ukash casino without seeing the method offered for that customer’s account.
Klarna at UK Casinos: How to Check Payment Support
That distinction matters because payment information can outlast the arrangement it describes. Pages are copied, payment brands change, and a casino’s available routes may differ between accounts. A claim that a site accepts prepaid payments does not, by itself, show that it accepts Ukash specifically. Nor does a list of UK casinos establish that each operator currently supports the same payment methods.
The practical check is narrower: identify the operator and account, then confirm the route being used for that transaction. The account holder’s name and payment details should belong to the same customer. In my experience, mismatches in basic ownership information are an avoidable source of questions and delays. Keeping the details consistent does not guarantee that a payment will be approved, but it removes one simple point of friction.
The same principle applies when a payment route is used more than once. A single named account used consistently for deposits and withdrawals is often the cleanest arrangement. Switching between people’s accounts or presenting a payment method whose owner differs from the casino account can make an otherwise straightforward transaction harder to reconcile. Keep it simple.
This is not a way to prove that Ukash is accepted. It is a way to make a confirmed transaction easier to follow. The method still needs to be available to the particular customer, and the operator’s terms and payment instructions govern what can be done. A general promise of “easy payments” says little about those details.
There is also a UK regulatory distinction behind the operator check. Remote gambling licensees selling into Great Britain must hold the relevant Gambling Commission licence, wherever the business is based. That status establishes the regulatory framework for the casino; it does not establish that a specific prepaid method is supported. Licensing and payment compatibility are separate questions.
Regulatory Status
Remote gambling licensees serving Great Britain must hold a Gambling Commission licence, though this regulatory status does not guarantee support for specific prepaid methods.
I would therefore read claims about Ukash casinos in the UK as claims to verify, not as a ready-made list of working options. The useful evidence is tied to the named operator, the account holder and the payment route actually available for the transaction. If those do not line up, the claim remains unconfirmed.
“Accepted” is a precise word. It should mean more than a logo, a broad payment category or an old description copied across several pages. For a real-money account, the dependable approach is to keep the customer identity consistent and rely only on a payment route the operator actually makes available to that account.
Prepaid Casino Deposits and Their Limits
A prepaid voucher separates the amount set aside for a casino deposit from a bank card or account balance. That can make it easier to keep a gambling payment within a chosen budget, but it does not make the voucher a general-purpose account. Paysafecard, for instance, is a deposit-only option: it can be used to fund an eligible casino account, but it is not a route for receiving withdrawals.
That distinction matters when comparing prepaid payment methods. A voucher’s role is narrow, and its presence in a payment list does not tell the whole story about the casino’s deposit conditions. The minimum accepted amount can differ by method, so a figure attached to one option should not be treated as the threshold for every way of paying.
A specialist casino review gives a starting minimum-deposit range of £10–£20, with the applicable amount depending on the selected payment method. This is a guide to the stated entry point, not a universal rule for every casino or voucher. The cashier’s displayed minimum is the practical figure for the transaction being considered; a voucher may not be usable for an amount below the threshold attached to that method.
Casinos That Accept Boku in the UK: How It Works
The payment screen is also where the amount and method meet. A player might have a voucher balance that feels suitable, but the casino’s minimum still governs whether the deposit can be submitted. Conversely, a minimum shown for a card or bank transfer does not establish that the same amount applies to a prepaid voucher. These are separate payment routes, and their terms can differ.
Prepaid does not mean unrestricted. Remote gambling licensees must prompt new customers to choose a financial limit before the first deposit, and they must make account-level limit controls accessible. That requirement concerns gambling-account controls rather than a particular voucher: using a prepaid method does not remove it. In practice, the voucher sets one boundary at the payment stage, while the account’s own controls address a different part of the process.
The word “simple” can obscure those distinctions. A voucher may avoid entering card details for a deposit, but the amount accepted still depends on the casino’s rules for that payment method. It is worth treating the minimum shown beside the selected option as specific to that route, rather than assuming that a prepaid deposit follows the same threshold as another method.
For anyone comparing prepaid casino deposits in the UK, the useful starting point is therefore modest: identify whether the voucher is deposit-only, then check the minimum attached to it. The £10–£20 range reported by a specialist review gives a broad indication, not a promise that every prepaid deposit will be accepted at either end of it. Small print matters.
Prepaid Vouchers
Deposit-only options, such as Paysafecard, used to fund an account but not for receiving withdrawals.
Account Controls
Mandatory financial limits and age verification required by licensees for all new customers.
Minimum Deposits
Method-specific thresholds, often ranging from £10–£20, which govern whether a deposit is submitted.
Checking Prepaid Payment Compatibility
A prepaid option can appear suitable for funding a casino account while offering no route for receiving a withdrawal. Those are separate functions. Compatibility has to be assessed across the full transaction, not inferred from the fact that a deposit can be made.
I have seen payment descriptions treated as if a method were a single, two-way pipe. In practice, the deposit and payout stages can follow different rules. A voucher may put funds into an account, while a later withdrawal is directed elsewhere. That does not automatically make the transaction impossible, but it changes which route is available and what checks may follow.
The central issue is the return of funds to their source. Returning money to the original payment source is a common anti-fraud and anti-money-laundering control. When a deposit method cannot receive a payout, the casino may need to use an alternative route and request further verification. The alternative is not necessarily available by default.
That is where closed-loop rules matter. The payment method used to deposit can shape the permitted withdrawal route, even if it is not itself usable for payouts. Before a transaction, the relevant terms need to answer two distinct points: whether the chosen method accepts deposits, and whether it can receive withdrawals. If it cannot, the account should make clear what alternative process applies. A vague label such as “prepaid” answers neither question.
Ownership details also matter. Using account information and a payment route belonging to the same customer reduces the chance that basic ownership checks create avoidable friction. If a different route is needed for a payout, additional verification may be required to establish that the account holder controls it. That is a control, not a promise that the alternative will be accepted.
Casinos that accept Maestro in the UK: what to check
Deposit ceilings are another part of compatibility, though they do not establish anything about withdrawals. A specialist review reports that maximum deposit amounts can differ by payment method and account status, including whether the cap applies to a transaction or a broader period. The displayed limit for one method should not be assumed to apply to another, or to every account. Check the terms attached to the selected route rather than treating a general payment summary as a universal rule.
Mobile access does not change these mechanics. A payment option shown on a phone still needs to work for the intended stage of the transaction, and the same source-return controls apply. A screen that accepts a deposit is not evidence that the payout path has been settled. Small distinction. Important one.
In my experience, the useful test is not whether a casino mentions prepaid payments, but whether its rules explain the complete route from deposit to withdrawal. Where the original source cannot receive money, the alternative and any verification requirement should be clear before funds are committed. That is the difference between a method that can start a transaction and one that fits the transaction end to end.
Is Ukash Still Available to UK Casino Players?
The presence of familiar payment brands at UK-facing casinos does not answer whether Ukash itself can still be used. Those are separate questions. A casino may support several current deposit routes while having no Ukash option; seeing other methods listed is not evidence that a Ukash payment will work.
Attention: The presence of other e-wallets like Skrill or Jeton at a casino does not confirm that Ukash is accepted.
That distinction matters because payment pages often describe a casino’s wider range of options, while the available methods can vary by operator and account. I have seen general payment claims read as if they confirmed a specific transaction route. They do not. A method’s name in a broad list is not the same as a working option for a particular UK customer.
The broader picture does show that some named alternatives remain in circulation. A specialist casino review describes Skrill as one of the more frequently encountered deposit methods at UK-friendly sites in 2026. The same type of review reports that Jeton is offered by a limited number of UK online casinos that year. These observations concern those products, not Ukash, and they should not be converted into a claim about Ukash acceptance.
Nor does the continued use of e-wallets or other payment categories establish that a prepaid brand is supported. Payment providers change their coverage, and operators can alter their own arrangements. The practical point is narrower: a casino’s willingness to accept one named method cannot be used as a proxy for another.
For UK players, the legal context also matters. Real-money online gambling is permitted at sites holding the relevant UK Gambling Commission licence; remote gambling licensees serving Great Britain need that authorisation. A payment brand appearing in material about a casino does not, by itself, establish either the operator’s regulatory status or the method’s availability.
I would treat “available” as a transaction-specific claim, not a description of a brand’s general presence in the market. The useful distinction is between a payment method that still appears at some casinos and one that a particular licensed casino currently accepts for the intended transaction. Ukash cannot be counted among the latter merely because other payment options remain in use.
Casinos That Accept CashToCode in the UK
No inference by association. A working Skrill or Jeton route says something about that route alone; it does not confirm Ukash acceptance.
What Replaced Ukash in the Prepaid Landscape?
The prepaid payment landscape includes products that may sound interchangeable in a casino cashier but do not necessarily serve the same role. Paysafecard is a prepaid voucher used for deposits only. That makes it a way to add funds, not a complete route for moving money both into and out of a casino account.
The distinction matters because “prepaid alternative” can describe a deposit option without meaning that it replaces every function associated with another payment product. A voucher’s presence in a cashier says something about deposits; it does not make the voucher a withdrawal method. In practical terms, the payment route has to be understood by what it supports, not just by the broad category attached to it.
Payz is a different point of comparison. EcoPayz rebranded to Payz in 2022. That is a change of brand name, not by itself proof that Payz is a prepaid voucher or a direct successor to Ukash. Treating a rebrand as a like-for-like replacement confuses two separate questions: what a product is, and whether a casino accepts it for a particular transaction.
I have seen payment names carry more weight in a headline than they do in the cashier. The important distinction is the function attached to the method. Paysafecard is deposit-only; EcoPayz became Payz. Neither detail establishes a direct Ukash successor.
This also keeps claims about UK casinos in proportion. A casino’s use of prepaid payment options does not establish that it accepts Ukash, nor does the existence of another payment brand prove a historical or technical link. Similar wording is not compatibility. Different job.
For anyone comparing prepaid products, the useful starting point is therefore modest: identify whether the named method is a voucher or a rebranded service, then treat its casino use according to the function actually stated. Paysafecard has a clear deposit-only role. Payz carries the name adopted by EcoPayz in 2022. Those are meaningful distinctions, but they do not make either product a confirmed replacement for Ukash.
What Happened to Ukash?
The question of what happened to Ukash is historical, not a shortcut to deciding whether a casino accepts it now. Those are separate matters. A payment method’s past cannot be reconstructed from a current casino cashier, and an old reference to Ukash does not establish what became of the service.
I would not attach a takeover, closure date, rebrand or successor to Ukash without a reliable account supporting that detail. A familiar pattern in payments is not evidence: one prepaid product can be replaced, renamed, absorbed into another service or simply disappear from a particular market. Treating any of those possibilities as Ukash’s history would turn a guess into a fact.
That distinction matters because “replaced” can mean different things. It might refer to a company’s corporate history, a product with similar functions, or a payment option a casino now lists. Those are not interchangeable. A prepaid voucher may offer a deposit route without being connected to Ukash, while a casino listing a range of payment methods says nothing by itself about Ukash’s history.
The practical point is modest. Ukash should not be described as having a particular successor or a definite corporate fate unless that claim can be substantiated. Nor does the absence of a confirmed historical account justify filling the space with a confident-sounding timeline. In payment writing, a neat story is easy to publish. It is not necessarily an accurate one.
Casinos That Accept AstroPay in the UK
There is also a difference between remembering a brand and establishing a usable payment route. An old article, forum post or saved image can preserve a name long after its context has changed. It cannot, on its own, show what happened to the service or prove that a UK casino currently accepts it. The historical question needs historical evidence; a live transaction question needs current, operator-specific information.
I have seen how quickly a payment label can outlast the practical details behind it. That is why I keep the claims separate: no assumed successor, no invented chronology, and no conclusion about present-day acceptance drawn from a name alone. A clean distinction.
Why Casino Payment Pages May Not Settle the Question
A casino payment page can give a useful outline without answering whether a particular Ukash payment is accepted now. In a specialist review of casino payment information, the listed categories included Visa, Mastercard, bank transfer, e-wallets and several cryptocurrencies. That is a broad description of payment options, not confirmation of every named service or voucher.
Casinos That Accept Solana in the UK: Key Checks
I read those categories as labels, not as a live promise. “E-wallets” does not identify which wallets are enabled, and a general reference to payment methods does not establish that Ukash is among them. The same caution applies when a page names familiar card networks or bank transfers: a category can be present while a specific route is unavailable for a particular transaction.
This distinction matters because public payment information may be written at a general level. It can help describe the kinds of payments a site discusses, but it cannot by itself settle whether a Ukash deposit is accepted at that moment. The wording may also leave unclear whether a method is available to UK customers or applies to the account in question.
I separate the page’s general description from the actual payment choice shown for a transaction. The first is background; the second is the relevant confirmation. Treating the two as interchangeable turns a broad mention into a claim it does not make. Small distinction. Real consequence.
Why can a fast-payout casino still delay my withdrawal?
A casino’s internal approval and account checks can hold up a payout, especially on a first withdrawal while verification is completed.
Are Visa and Mastercard deposits definitely debit cards?
No. UK casinos commonly accept Visa and Mastercard debit cards, but check the cashier and the card product you are using; credit-card gambling is prohibited at UK-licensed casinos.
Which method has the lowest fees?
There is no universally cheapest method. Compare the casino’s charges, provider or bank fees, currency-conversion spread and any network costs for the payment you plan to make.
Why must withdrawals return to the deposit method?
Returning funds to the original payment source is a common anti-fraud and anti-money-laundering control. Using another route may involve additional verification.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest. The casino’s approval process and whether your account is verified also affect the wait.
Do UK casino withdrawals require verification?
Verification may be required before a withdrawal is approved, particularly for a first payout. Having a fully verified account can help avoid delays.
Is Skrill available?
Yes, Skrill is available at some UK-friendly casino sites. Its availability and bonus eligibility can vary, so check the cashier and the promotion’s terms.
Material created by the team Golden Mister