
A casino’s general payment information may not match the options shown in a UK account’s live cashier.
Entropay and UK Casino Payments: What Online Availability Actually Means
Entropay can appear in material about online casinos without being a payment option a UK player can select at the point of deposit. Those are different claims. A brand name on a casino page, in a payment-method roundup or in an old discussion may show that Entropay has been associated with gambling payments; it does not establish that a particular casino currently accepts it.
That distinction matters because payment pages can outlive the arrangements they describe. An operator may change its available providers, remove a method from some markets, or show different options according to account details. A general reference to Entropay therefore cannot stand in for a live cashier option. In my experience, the cashier is where a payment claim becomes operational—or fails to.
For anyone looking for UK casinos that take Entropay, the useful question is not simply whether the name appears online. It is whether the method is offered for a UK account, at that casino, at the time of the transaction. Without that confirmation, calling a site an Entropay casino risks turning a reference into a promise. That is a poor basis for choosing where to play.
If you are looking for a UK casino associated with Entropay, check that the payment method is currently available before signing up. The payout timeframe shown for each operator is useful to consider, but it does not confirm Entropay acceptance.
1. Zombillion
Payout speed: 1-3 business days
Zombillion lists a payout speed of 1–3 business days. This timeframe alone does not confirm whether Entropay is accepted.
2. SlotoSport
Payout speed: 1-3 business days
SlotoSport lists payouts as taking 1–3 business days. Check directly whether Entropay is currently available as a payment option.
3. Dieselwin
Payout speed: 1-3 business days
Dieselwin has a stated payout speed of 1–3 business days. No payment-method details are provided here to confirm Entropay acceptance.
4. WinBeast
Payout speed: 1-3 business days
WinBeast lists a payout timeframe of 1–3 business days. The available information does not establish whether it accepts Entropay.
5. Britsino
Payout speed: 1-3 business days
Britsino’s stated payout speed is 1–3 business days. Verify Entropay availability with the operator before relying on it as a deposit method.
6. Revery Play
Payout speed: 1-3 business days
Revery Play lists payouts at 1–3 business days. This is the only operator detail provided, so Entropay acceptance is not confirmed.
7. NightLuck
Payout speed: 1-3 business days
NightLuck has a listed payout speed of 1–3 business days. Check its current payment options to establish whether Entropay is accepted.
8. NightWin
Payout speed: 1-3 business days
NightWin states a payout timeframe of 1–3 business days. The information available here does not confirm Entropay support.
9. BeOnBet
Payout speed: 1-3 business days
BeOnBet lists payouts as taking 1–3 business days. Confirm directly whether Entropay is available before choosing a payment method.
10. Chanze
Payout speed: 1-3 business days
Chanze has a stated payout speed of 1–3 business days. No information is provided here about whether it accepts Entropay.
A payment name is not a confirmed route
Casino payment information is often presented in broad terms. A site might publish a general list of brands, while the options shown to an individual account depend on the market and the cashier’s current configuration. The distinction can be easy to miss: a method mentioned in descriptive text is not necessarily enabled for deposits, and a name appearing in an old list does not prove it remains available.
Entropay-related pages can also blur different meanings of “accepts”. The phrase might refer to a past arrangement, a third-party payment service, or a general association with a payment brand. Those descriptions do not necessarily mean that Entropay itself appears as a selectable option for a UK customer. Nor do they show what transaction the casino would support. The wording sounds definite. The mechanics may not be.
A “best” or “top” label does not resolve the underlying question. A casino can only be described as accepting Entropay when the payment route is genuinely available to the relevant UK account, rather than inferred from a headline or a broad payment-method description.
Why UK context matters
Payment availability is not interchangeable across markets. A casino may serve customers in more than one jurisdiction, but its payment arrangements can differ between them. UK-facing information needs to be read as UK-facing information, rather than assumed from a page written for another audience.
Payments · Casino sites that accept EcoPayz in the UK: how to check
The same caution applies to card references. Affiliate casino reviews may list Visa or Mastercard, but that list does not prove that a particular card product is currently eligible in a UK cashier. The displayed options and the underlying card type both matter. A brand-level mention is not a universal acceptance statement.
Currency is another detail that can be obscured by general payment descriptions. Affiliate pages may state that GBP is supported, but the account currency still needs to be established before a first transaction if conversion is to be avoided. A pound symbol in a description does not, by itself, show how a specific account is configured.
These details illustrate the broader point: payment claims have a market, an account and a moment attached to them. Remove those conditions, and a statement can sound more certain than it is.
Treat “Entropay casino” as a claim to verify
The phrase “Entropay casino” is often used as shorthand for a casino believed to support the method. Shorthand is convenient for a heading, but it can collapse several separate questions into one. Is the named method currently offered? Is it offered to UK customers? Is it available on the account being used? Is the description about a deposit route or merely a reference to the brand? Each distinction changes what “accepts” means.
I would not treat a casino as confirmed solely because an Entropay reference appears in promotional or informational copy. That is not a finding that the reference is false; it is a boundary on what the reference proves. Payment systems change, and the cashier—not the language around it—determines what can actually be selected.
A reference to Entropay in promotional or informational copy is not a confirmation of availability; only the live cashier determines what can actually be selected.
For UK readers, the practical standard is a current, UK-specific indication in the casino’s own payment interface. Anything less may be a lead, not confirmation. No inference should be made from a casino’s general reputation, a page title or a list that does not identify the account and market it describes. The name can travel further than the payment option.
How to Check Whether a Casino Accepts Entropay
A payment method named on a casino page is not the same thing as a method available to a particular account at the point of deposit. I treat the live cashier as the useful check. It shows what the operator is presenting for that account now, rather than what a general payment page, review or old reference says may have been supported.
That distinction matters for searches about UK casinos accepting Entropay. A mention attached to a casino’s name can survive after its payment arrangements have changed, or may describe a different market. It can also be copied from one page to another without anyone checking the actual deposit screen. Search-result snippets are especially poor evidence: they compress context and rarely show when a payment detail was last confirmed.
Check the cashier for the account in question
The practical test is to sign in to the casino account and open its deposit cashier, without submitting a payment. The relevant question is whether Entropay is presented there as an available method for that account. A general page listing payment brands is weaker evidence because it may cover more than one country, account type or transaction route.
Casinos That Accept Ethereum in the UK: What to Check
The cashier should be read in context. A method may appear in a broad list but not be selectable; it may be selectable only after an account is logged in; or the interface may show a payment route that is not available to a UK customer. The difference between a logo and a working option is plain, but it is where many outdated claims begin. A button is more informative than a logo. A successful authorization is stronger still, though there is no reason to submit a deposit merely to test a claim that the cashier does not clearly support.
I would also check the operator’s payment information against the cashier rather than treating either as a substitute for the other. If the page says one thing and the account screen says another, the discrepancy needs resolving with the operator before money is moved. The cashier is the immediate compatibility check; written confirmation from support can clarify an ambiguous screen. Neither an old review nor a general list establishes that a particular payment will be accepted now.
Treat old payment references as leads, not confirmation
A dated article, forum post or archived page can explain why Entropay appears in a casino-payment discussion. It cannot establish present availability. Payment arrangements change, and material written for another country can be mistaken for a UK offer. Even a recent-looking page may describe a general range of methods rather than the methods enabled for an individual account.
Do
- Treat old payment references as leads to investigate
- Use the live cashier as the primary verification tool
- Check if the method is offered specifically for UK accounts
Don’t
- Turn a historical mention into a current recommendation
- Assume availability based on outdated articles or forum posts
- Rely on search-result snippets as evidence of current support
I avoid turning a historical mention into a current recommendation. The wording “accepts Entropay” sounds definitive, but it may conceal several unanswered questions: whether the statement refers to the UK, whether the method is still active, and whether it applies to the account being checked. Those are not small qualifications. They determine whether the payment route can actually be used.
A specialist review can be useful as a pointer to what to inspect, but it is not the cashier itself. The same caution applies to a payment-method table on an operator’s site if it does not make clear which market or account it covers. If Entropay is absent from the live deposit options, a historic mention does not turn that absence into acceptance.
Match the payment identity to the casino account
Availability is only one part of a clean check. The casino account and the payment route should belong to the same customer. Matching basic ownership details reduces the chance that a transaction is delayed or questioned because the names or account details do not line up.
This is a simple point with practical consequences. A payment account held by someone else, or details that differ from the casino profile, can create avoidable friction even where the payment brand itself is supported. The cashier can show whether a route is offered; it cannot make mismatched ownership details consistent. The account holder and the payment holder should therefore be the same person, with accurate information entered on both sides.
Casinos That Accept AstroPay in the UK
I would not assume that a familiar brand name settles eligibility either. A specialist review may list Visa and Mastercard, for instance, but that is not proof that every card product or every UK account can use them. Current UK availability and card-product eligibility need to be checked in the cashier. The same principle applies to any payment label: what matters is the specific option presented to the account, not the brand’s general presence elsewhere.
What counts as a useful confirmation
A sensible record of the check is modest: the account was logged in, the deposit screen was opened, the method was or was not selectable, and any uncertainty was put to the operator before a transaction. This is not a guarantee that a payment provider will authorize a later attempt. It is a way to separate current account-level information from recycled claims.
If the cashier does not show Entropay, the accurate conclusion is that it is not being offered there at that time—not that every casino has the same policy, and not that an old reference proves otherwise. If the cashier does show it, the displayed terms and account ownership still matter. No guesswork.
Casino Deposit Options When Entropay Is Not Shown
When Entropay is absent from a casino cashier, the useful question is not which label sounds closest, but which payment routes are actually offered for that account. A method shown in a general payment description may not be available to every customer or for every transaction. The cashier is where the available choices become concrete.
That distinction matters because an alternative is not a substitute in the technical sense. A debit card, bank connection or mobile wallet has its own setup and processing route; none should be treated as Entropay under another name. I would read the options as separate ways to fund an account, with their own conditions.
When Entropay is absent, other available routes like debit cards or mobile wallets are separate funding methods and should not be treated as substitutes or alternatives under another name.
Debit cards
Debit cards are a familiar route at UK casinos. Visa and Mastercard debit cards are commonly accepted, though a logo on a payment page is not enough to establish that a particular card product will work. The cashier’s current selection is the practical reference.
The distinction between debit and credit is important in Britain. A payment made from a debit balance is not the same as a credit-card payment for gambling, which remote gambling licensees cannot accept. A card brand alone does not settle which kind of card is being used. The account and card product matter.
From the payment desk, card deposits are straightforward only when the details line up: the card must be available for the transaction, and the casino must be able to match the payment to the account. A failed card attempt does not prove that all cards of the same brand are unavailable. It may reflect the issuer, the specific card product or the casino’s current processing setup. No clean universal answer.
Open banking and bank transfers
Open banking gives a customer a way to authorise a payment through a bank connection, while a bank transfer sends funds through the banking system. These are related in the sense that both involve a bank account, but they are not necessarily presented or processed as the same cashier option.
A specialist casino review has described open banking and bank transfers as routes that can provide instant deposits, with fast withdrawals at many sites. That is a description of what those routes may offer, not a timing promise for every casino or transaction. The particular service, the bank and the operator’s process can affect what happens.
Casinos That Accept Giropay in the UK: Payment Checks
For a deposit, the useful distinction is whether the cashier offers a direct bank connection or asks for a transfer using bank details. One may require an authorisation step; the other may involve the customer’s banking app or transfer service. The on-screen instructions define the route. A general reference to “bank transfer” does not guarantee that every transfer format is supported.
I have seen payment wording make a bank route sound like one uniform product. It is not. The name can refer to different services, and the deposit flow reveals more than the label. The confirmation screen is the point at which the amount, recipient and payment route should make sense together.
Apple Pay
Some UK Gambling Commission-licensed casinos accept Apple Pay for deposits. Its presence depends on the casino and the cashier, so it should not be assumed from the fact that a site takes cards. Apple Pay is a separate option in the payment flow, even where a card sits behind the wallet.
That separation is practical, not cosmetic. A customer may see a card brand listed but not see Apple Pay, or the reverse. What matters is the route actually offered for the account at that time. A deposit option should not be inferred from a logo elsewhere on the site.
Reading the cashier without overreading it
Payment pages often group methods under broad headings, but the displayed choices are more useful than promotional wording. A route may appear only after signing in, or may not be available to a particular account. The cashier is not merely a set of logos; it is the working menu for that deposit.
Debit Cards
Commonly accepted Visa and Mastercard debit cards, provided the specific card product is eligible in the cashier.
Open Banking
Direct bank connections or transfers that may provide instant deposits and fast withdrawals.
Apple Pay
A separate payment flow available at some UKGC-licensed casinos, independent of general card logos.
For someone looking for Entropay casino deposits in the UK, the sensible interpretation is narrow: if Entropay is not displayed as an available method, another listed route is simply another route. Debit cards, bank-based options and, at some licensed casinos, Apple Pay describe the payment landscape. They do not establish Entropay acceptance, nor do they make one method interchangeable with another.
I avoid treating a familiar brand as proof of compatibility. Availability can differ between the site’s general payment information and the options presented during a transaction. The method visible in the live cashier is the one that can be assessed for that deposit. Straightforward, but decisive.
Deposit Amounts, Limits and the UK Pre-Deposit Check
A specialist casino review puts the minimum deposit commonly encountered in the £10–£20 range, with the amount depending on the payment method. That is a reference point, not a tariff shared by every casino. The cashier sets out the threshold for the selected route, and the figure can differ between methods at the same site. An Entropay reference elsewhere does not establish what its minimum would be in a UK casino cashier.
Minimums are only one part of the payment rules. A cashier may also impose a maximum for a single transaction, while separate daily or monthly caps can apply. Those limits can depend on the payment method and account status. The amount shown for one route should not be treated as the limit for another, or as a promise that the same ceiling will apply to every account.
Casinos That Accept Interac in the UK: Payment Terms
This is where payment controls and safer-gambling controls are easy to confuse. A deposit limit in a cashier governs what can be processed through a payment route. A financial limit on the gambling account governs how much a customer chooses to make available for gambling. They serve different purposes and may appear in different parts of the account.
The first-deposit prompt
UKGC rules require remote gambling operators to prompt new customers to set a financial limit before their first deposit. Operators must also provide accessible account-level controls for setting limits. This is not a payment-method minimum or a maximum imposed by a bank, card issuer or cashier. It is an account-level safeguard, presented before the first deposit can be made.
I have seen these distinctions get lost when payment pages place several figures close together. One figure can be the minimum needed to start a transaction; another can be a payment cap; a separate control can be the customer’s own financial limit. Similar labels do not make them interchangeable. The function matters.
The prompt is part of the UK account process, not a special condition attached to Entropay. If a payment option appears in a cashier, its stated deposit threshold still needs to be read separately from the financial-limit controls. Finding one does not answer the other.
Reading the figures accurately
A minimum tells only whether a proposed deposit meets the entry threshold for that method. It does not reveal the account’s maximum, whether a transaction cap applies, or what financial limit has been set. Likewise, a displayed maximum does not override an account-level limit. The cashier and account controls have separate jobs.
Financial Limit vs Deposit Limit
A deposit limit in the cashier governs the amount processed through a specific payment route, whereas a financial limit is an account-level safeguard set by the customer before their first deposit as per UKGC rules.
Limits can also be conditional. Payment method and account status are both relevant to maximum deposit limits, so a figure seen before signing in may not settle what applies to a particular account. The operative amount is the one presented for the selected method and account at the time of the transaction.
For a search centred on Entropay, that distinction prevents a familiar mistake: treating a general deposit range as proof that a particular method is accepted or has a particular limit. A stated minimum is not compatibility evidence. Nor does a financial-limit prompt confirm which payment routes are available. Each control answers a narrower question.
The practical reading is straightforward: identify the selected method’s minimum and any transaction or account caps, then distinguish those from the financial limit set on the gambling account. The amounts may sit near one another on screen. They are not the same control.
Payment Methods for UK Players: Prepaid Vouchers and E-Wallets
A prepaid voucher and an e-wallet can both appear in a casino cashier, but they are not interchangeable labels. Paysafecard is a prepaid voucher used for deposits only. Skrill, Neteller and PayPal are e-wallet brands; whether any one is offered depends on the site. That distinction matters when comparing payment routes, and it does not establish that Entropay is accepted.
A voucher is presented as a prepaid deposit route. Its deposit-only status is the key practical limit: it should not be treated as an all-purpose account for casino transactions. An e-wallet is a separate payment service, and the cashier may offer it under its own brand. Seeing an e-wallet option therefore says nothing by itself about whether a prepaid voucher is available, or whether Entropay can be used.
Casinos that accept Maestro in the UK: what to check
I have seen payment pages make the methods look like a neat menu of equivalent buttons. They are not. The label describes a route, not a promise that the route suits every promotion or every account. Availability can differ from one casino to another, and promotional terms can add another condition.
For Skrill and Neteller, specialist casino reviews have reported that these wallets are offered at some sites and may be excluded from promotions. That is a site-specific condition, not a rule to assume across the market. The relevant bonus terms determine eligibility. A payment button and a promotion badge can coexist while the terms still exclude a particular wallet.
Specialist casino reviews have also described PayPal as valued for speed and convenience, while noting that it may not qualify for bonuses. This should be read as a reported feature of particular offers, not a dependable market-wide promise. If a bonus matters, the payment-method clause is more decisive than a general description of PayPal.
For someone looking at Entropay casino payments in the UK, the useful distinction is between the named method and the category around it. A voucher, an e-wallet and an Entropay reference are not interchangeable evidence. A casino listing Skrill, Neteller or PayPal has identified those services; it has not thereby identified Entropay. Nor does a mention of prepaid vouchers establish that Entropay is one of them.
Prepaid Vouchers
Examples like Paysafecard, which are used strictly for deposits only.
E-Wallets
Services such as Skrill, Neteller, and PayPal, which may be excluded from certain casino promotions.
Entropay References
Informational mentions that do not establish the availability of vouchers or e-wallets.
The practical reading is narrow: Paysafecard is deposit-only; some sites offer Skrill or Neteller, with promotion exclusions reported by specialist reviews; and PayPal may also be excluded from bonus eligibility. None of these statements determines Entropay availability. Separate labels. Separate terms.
That is why payment descriptions should be read as descriptions of named routes, not as broad assurances about every payment brand in the same family. A cashier’s exact option and the offer’s conditions are what define the choice. The category alone does not.
Entropay Casino Searches in the UK: The Credit-Card Boundary
The important distinction is not the name attached to a payment route but whether it amounts to credit-card funding for gambling. In the UK, remote gambling operators cannot accept credit-card payments for deposits. The regulator introduced that ban on 14 April 2020, and it remains in force.
Routing a credit-card payment through a money service business does not make it acceptable. The restriction covers that route too. A payment intermediary cannot turn a prohibited credit-card deposit into a permitted one simply by appearing between the card issuer and the casino.
That is the boundary relevant to Entropay-related casino payments. A reference to Entropay does not establish that a UK casino can accept a particular transaction, nor does the brand name itself settle whether the underlying funds are credit. The route and funding source matter. I have seen payment labels create false confidence: a familiar name can make a transaction look routine while the underlying card type remains decisive. The label is not the test.
Casinos That Accept Tether in the UK: Payments
Debit cards sit on the other side of the distinction. UK casinos commonly accept debit cards, including Visa and Mastercard. That does not mean every card carrying those brands will work for every customer or transaction; it means debit-card payments are not covered by the credit-card gambling ban simply because they use a card network.
The practical point is narrow. A casino cannot lawfully accept a credit-card deposit, whether the payment is direct or routed through a money service business. A debit-card deposit may be available, subject to the casino’s actual payment arrangements. The two should not be treated as interchangeable merely because both begin with card details.
In my experience, this is where payment wording can blur a clear rule. “Card accepted” says little unless the card type is understood. Credit is barred for gambling deposits; debit is a separate category. Clear enough.
Payment Security: Why the Deposit Route Can Affect a Payout
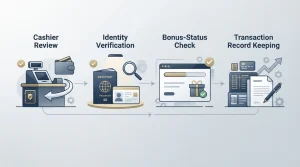
A deposit is not just money arriving at a casino account. It also creates a record linking the customer, the payment instrument and the source of funds. When a withdrawal is requested, that record helps the remote gambling licensee check that money is going back through a legitimate route rather than being redirected to an unrelated account.
UK anti-money laundering rules generally point towards returning funds to the original payment source. This is part of the closed-loop approach: the deposit and payout are connected, making it harder to use a gambling account to move funds between people or disguise their origin. It is a security control, not a judgement about the customer.
Credit Card Ban
UK remote gambling operators are prohibited from accepting credit-card payments for deposits, including those routed through money service businesses.
In operational terms, matching ownership matters. If the casino account is in one person’s name but the payment account appears to belong to someone else, the transaction can raise questions that have to be resolved before funds are released. A consistent named account for both deposit and withdrawal gives the operator a clearer trail. Fewer basic ownership questions. Less friction.
That is why I treat “supported” as more than a button appearing in a cashier. A payment route can be accepted for a deposit yet still sit within checks that govern where a payout goes. The operator’s controls, the payment provider’s records and the account details all need to fit together. An Entropay reference in a casino description, for instance, would not by itself establish that a particular deposit and withdrawal path is available or suitable.
Where returning funds to the original source is not possible, an alternative route may involve additional verification. That can mean the operator needs to establish who controls the alternative account and why it is being used. It is not a reason to assume that any different destination will be accepted automatically.
I have seen payment questions become avoidable delays simply because the name or ownership details did not line up cleanly. The sensible internal rule is straightforward: use an account held in the same customer’s name, keep the payment trail consistent, and understand that security checks can still apply. This does not remove the operator’s responsibility to review a transaction, but it reduces the chance that a mismatch creates extra work.
The point is traceability. A clean route gives the casino a coherent record from deposit to payout, while an unexplained change can require more scrutiny. That is the mechanism behind the rule.
Casinos That Accept Google Pay in the UK: What to Check
Confirming Payment Compatibility Before Depositing
A payment option is not a complete route merely because it appears in a casino’s description. The cashier is the working record: it shows which methods are enabled for that account and whether the displayed option applies to the transaction being made. A specialist casino review may list Visa or Mastercard, for instance, but that does not establish current UK availability or eligibility for every card product. Those details need to be checked in the live cashier.
I learned to separate three questions that promotional wording tends to compress into one: can the method fund the account, can a withdrawal return through it, and does the account holder match the payment owner? A deposit button answers only the first. If the cashier gives no clear withdrawal route, the method has not yet been confirmed as a complete payment arrangement. Another route may be required, with additional checks.
The ownership match is plain but consequential. When the casino account details and payment route belong to the same customer, basic discrepancies are less likely to interrupt a transaction. Different names or account details can turn a routine payment into a verification issue. Keep the record consistent.
Wallets need a separate eligibility check. UK remote gambling operators cannot accept wallet payments where the wallet permits credit-card funds to be used for gambling. A wallet’s presence in a cashier therefore does not by itself settle whether a particular funding route is permitted. The relevant question is not only whether the wallet can send money, but how it was funded and whether that use is allowed.
Confirming Payment Compatibility
- Check if the method is selectable in the live cashier
- Verify that a withdrawal route exists for the method
- Ensure the payment account holder matches the casino account name
- Confirm the wallet does not use prohibited credit-card funding
I would treat any method as confirmed only after checking both sides of the cashier flow and the account ownership requirements. For a search for casinos accepting Entropay in the UK, the same standard applies: a reference elsewhere is not confirmation that the method is currently usable for deposits and withdrawals. No shortcut.
Casino Deposits: Currency, Fees and the Cost Behind the Button
A deposit button shows the amount being sent, not necessarily the full cost of sending it. I have seen payment comparisons reduced to a single visible charge; that leaves out costs that can arise elsewhere in the transaction.
A specialist review identifies several possible components: a casino charge, a payment-provider fee, a fee from the card issuer or bank, a currency-conversion spread and, where relevant, a network fee. Which ones apply depends on the route and the accounts involved. A casino may show no deposit fee while a bank or provider applies its own charge. The reverse is possible too: a provider may show a clear fee, while the exchange rate carries an additional cost that is less obvious.
Currency matters when the casino account and payment account do not use the same currency. The transaction may be converted by the casino, the provider or the bank, and the rate used can affect the amount finally debited. A specialist review notes that the conversion spread can exceed a visible flat fee. That is why “no fee” is not the same as no cost.
For a deposit associated with Entropay, the same calculation would apply only if the method were actually offered and usable for that transaction. A name appearing in payment information does not establish the exchange rate, fee structure or final debit for a particular account. Those details belong to the live payment flow and the relevant provider terms.
Casinos That Accept iDEAL in the UK: What to Check
I compare the total amount leaving the funding account with the amount credited to the casino balance, then account for any separate bank or provider charge. The comparison is specific to the transaction, not a universal ranking of methods. One headline fee tells little.
Withdrawals After an Entropay Casino Deposit
A deposit appearing straight away says little about when a withdrawal will arrive. I have seen payment journeys treated as one process from the outside; operationally, they have separate stages. The casino first reviews and approves a withdrawal, then the payment provider or bank handles the transfer. For a first payout, KYC checks can add time while the account is verified.
A specialist casino review notes that a card deposit may be instant while the resulting payout takes several business days. That is a useful distinction, not a fixed timetable: the casino’s approval process and the payment route both matter. The same review identifies PayPal, open banking and debit cards connected to fast payout systems among the quicker withdrawal options, but that does not establish that any particular casino supports each route for a given account.
Casinos that accept Monzo UK: what to verify
For a deposit described as Entropay, the key point is not to assume that the same branded route remains available for withdrawals. UK anti-money laundering controls commonly direct winnings back to the original payment source. Where that cannot be used, the casino may require another approved route and further checks before releasing funds. The cashier’s withdrawal options, rather than an old payment reference, show what is supported at the time.
Bank transfers have their own timing variables: cut-off times, weekends and currency conversion can affect delivery. A fast deposit is not a fast payout. The distinction matters.
I would treat the displayed processing estimate as the casino’s part of the journey, not necessarily the moment funds reach a bank account. Verification, the chosen method and the receiving provider all sit between approval and receipt. For an Entropay-related deposit, no withdrawal should be assumed until the live cashier confirms an available route and its conditions.
Why must withdrawals return to the deposit method?
Returning funds to the original payment source is a common anti-fraud and anti-money-laundering control. Using a different route may require additional verification.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest options. The casino’s approval process and your verification status also affect how soon funds arrive.
Can I deposit in GBP?
Yes, GBP is supported, but check that your account is set to pounds before depositing to avoid currency conversion.
What is the current minimum deposit?
The minimum deposit usually starts at £10–£20, depending on the payment method.
Why can a fast payout casino still delay my withdrawal?
A casino must approve the withdrawal, and first payouts may take longer while verification is completed. Processing can also be affected by delivery times, cut-off times and weekends.
Do UK casino withdrawals require verification?
Yes, verification may be required, particularly before a first withdrawal. A fully verified account can help avoid delays.
Which method has the lowest fees?
There is no universally cheapest method. Compare any casino and provider charges, bank or issuer fees, currency-conversion spread and network costs for your transaction.
Are fast casino withdrawals guaranteed?
No. Even with a fast payment method, the casino’s approval process and account verification affect payout speed; bank transfers can also be affected by cut-off times and weekends.
Material created by the team Golden Mister